Sunday Spotlight
Real Talk for Real Estate Pros · Capital Region
The Fed raised rates. Your mortgage rate might drop.
Two different numbers, two different markets. Almost everybody is reading the wrong one.
This week's take
The Fed does not set your mortgage rate.
Wednesday at two o'clock the Fed raised its benchmark rate a quarter point, to a target range of 3.75% to 4%. First increase since 2023. The vote was unanimous, twelve to nothing. By Wednesday night phones were going off all over the Capital Region, agents and clients and people who are not buying anything at all, and every message said some version of the same thing: did we just miss it?
Here is the answer nobody gives, because it takes more than a headline to explain. The rate the Fed just moved is what banks charge each other to borrow overnight. Nobody buying a house is borrowing overnight. A mortgage is 30-year money, and 30-year money is priced off the ten-year Treasury. Two different animals on two different clocks.
How different? Late in 2024 the Fed cut three times in a row. Mortgage rates went up. Not sideways, up. It happened again through 2025. Anybody who said "wait for the Fed to cut and your payment drops" has already been wrong twice, and got away with it because nobody went back and checked.
Now the strange part, and this is the useful part. One of the forces that pushed the ten-year over 5% this week, its highest level since 2007, was a Fed that kept looking past inflation while oil ran and tariffs worked their way through. A Fed that finally moves takes some of that anxiety out of the bond market. That is not a promise of lower mortgage rates. It is a real possibility that this hike relieves upward pressure rather than adding to it.
Back when I was selling, Fed day felt like a verdict. Everyone stood around the office waiting to find out what the market was going to do to us. Then I got to the lending side and watched what actually happens: the bond market moves first, prices the meeting in for weeks, and by two o'clock Wednesday the news is usually already in the rate. This week proved it twice over. Rates improved for a moment after the announcement, then gave it all back before the press conference even ended.
Worth sitting with the next set of numbers, because they do not agree with each other.
The Fed meeting is the headline. The ten-year Treasury is the price.
The numbers that actually move the payment
What the Fed did Wednesday
Read those in order and the story is not the hike. It is the dot plot. The committee is telling you it is not done, and the bond market is listening to that far more closely than to the quarter point itself.
The 30-year fixed, depending on who you ask
That is a 61 basis point spread between the lowest published number and the highest, on the same week, for the same loan. All four are accurate. They survey different lenders, on different days, with different assumptions about credit, down payment and points baked in.
On a $400,000 loan the difference between the top and bottom of that range is roughly $165 a month. Which means the person who read 6.76% on the news and the person who read 7.37% on their phone are arguing about the same week, and neither number is actually anybody's number. Yours depends on your credit, your down payment, your property and the day you lock.
The Wednesday night text. "Saw the Fed raised rates. Should we just wait until things settle down?"
Wrong question, reasonable instinct. Some version of it landed in a lot of inboxes this week. What it is really asking is whether you are about to overpay, and whether waiting is free. Waiting is not free here. The dot plot says most of the committee expects at least one more increase, and the Capital Region is not sitting still while anyone waits.
Median sale price in Albany ran $317,500 in July, up 7.26% year over year, with homes moving in 56 days at 104.61% of asking. Just under 65% of homes sold above ask, up from 45% a year earlier, and price reductions fell from 39% to 28%. None of that changed Wednesday at two o'clock.
Payment figures are illustrations on a 30-year fixed principal and interest basis using the published averages cited above. They exclude taxes, insurance and mortgage insurance. Not a quote, not an offer, not a commitment to lend. Every file prices differently. [Brian to verify local figures against current GCAR monthly indicators before send.]
Nobody is really asking about monetary policy. They are asking whether they just missed something.
What to do with it this week
Four different people are reading this. Find yours.
For realtors
Answer the question under the question.
Nobody wants a lesson on the federal funds rate. They want to know if waiting helps. Give them the short version: the Fed moved the overnight rate, mortgages follow the ten-year Treasury, and those two have gone opposite directions twice in two years.
Then hand them something concrete. Send the buyer to me and I will put their actual payment at today's pricing next to what it looks like if the committee follows through on another increase. A number they can decide against beats a headline they can worry about.
For buyers
Watch the ten-year, not the Fed.
If you only track one thing, track the ten-year Treasury yield. It crossed 5% this week. When it moves, mortgage pricing moves with it, usually within a day or two. Fed meetings get the coverage, but the ten-year is what your rate is built on.
And get your pre-approval re-priced. Anything written before this week was built on different math, and you should be shopping against the number that exists right now, not the one from August.
For sellers
Hike headlines pull fence-sitters off the fence.
Counterintuitive, but a Fed that says it may raise again does more to create urgency than any listing copy you could write. Buyers who were casually waiting for relief just heard the committee tell them relief is not the plan.
If you have been waiting for spring, understand who is shopping right now. Just under 65% of Albany homes sold above asking last month. The serious buyers are out, and they are motivated by exactly the news everyone else is reading as bad.
For everybody else
Somebody you know is getting this wrong right now.
Not buying, not selling, no plans either way? Still worth two minutes of your Sunday. Because you know somebody who is. The kid who has been renting and just decided this week is the wrong week. The parent sitting on a paid-off house with no idea what the next one costs. The friend who got pre-approved in August and thinks that number still holds.
Forward this to one of them. Not as a favor to me. Because what they heard on the news was the overnight bank rate, and that is the wrong number to make a six-figure decision on. Thirty seconds of your time saves somebody a bad assumption they would have carried for a year.
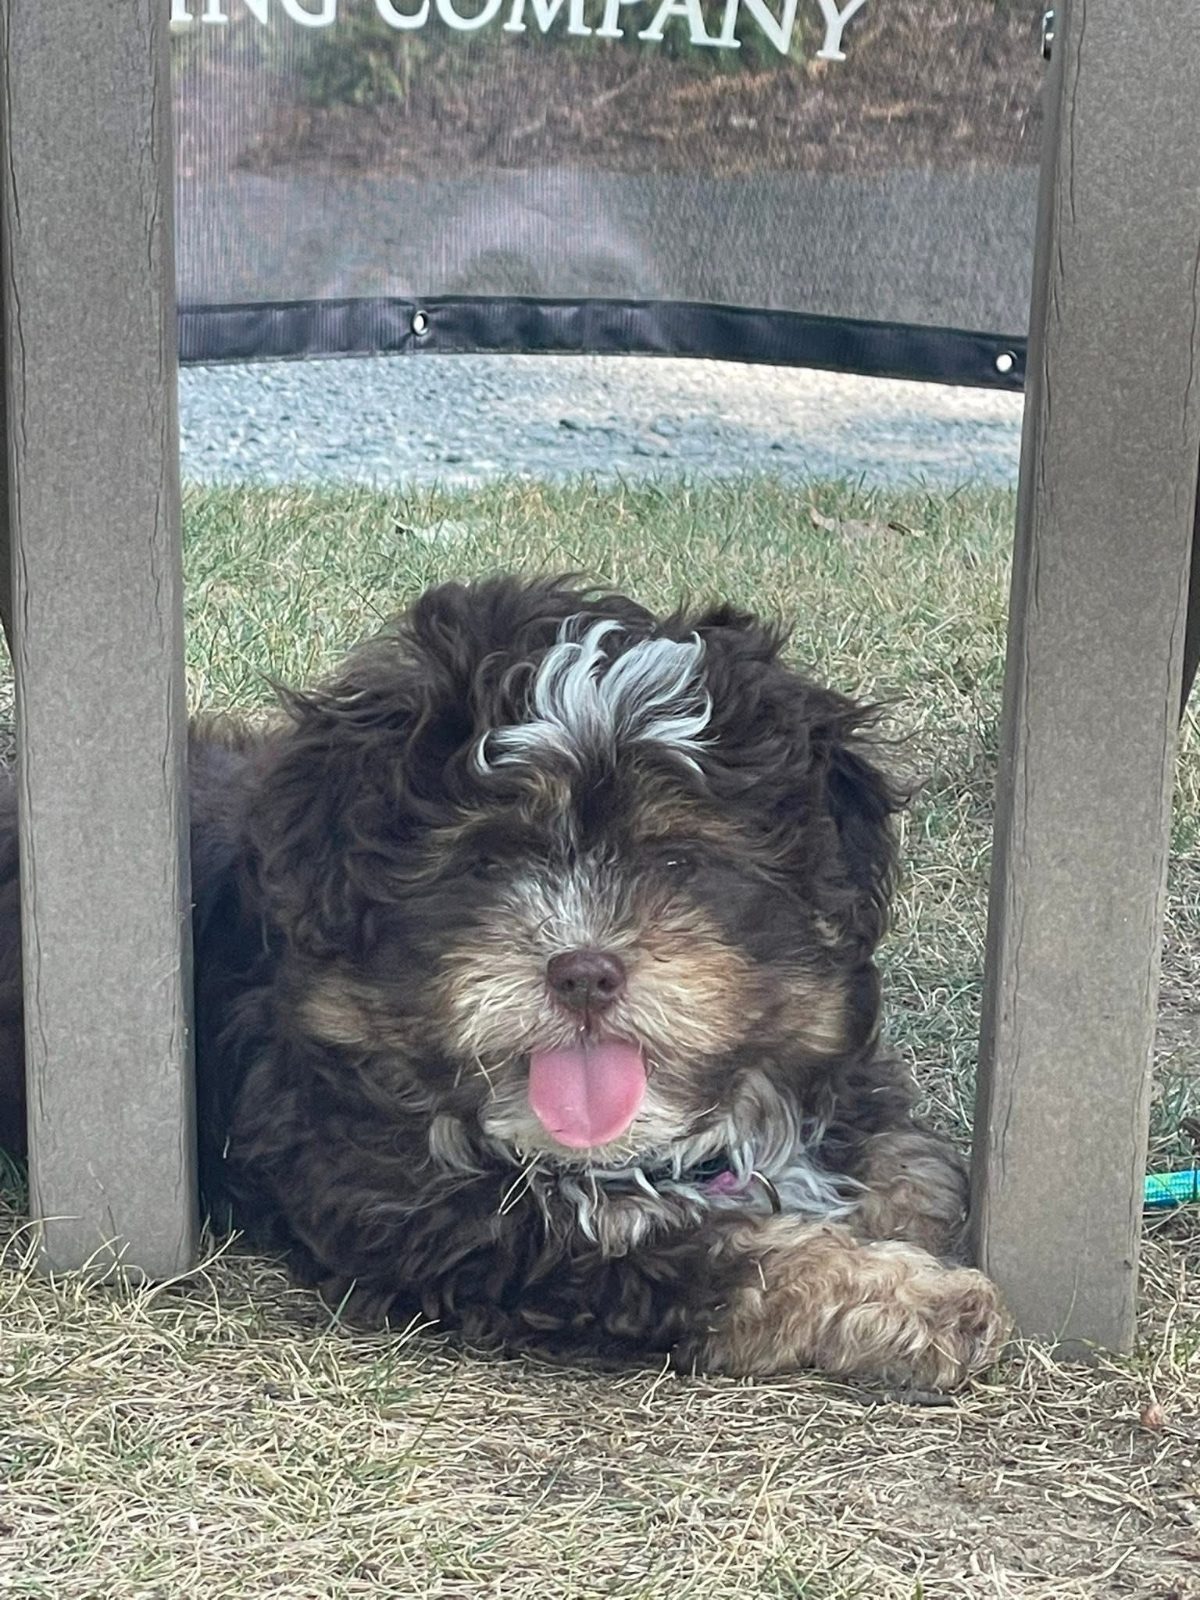
Penny's Corner
Words of wisdom, from under Dad's desk
Dad watched the TV say one number and his computer say a different number, and then he explained both to somebody on the phone for 20 minutes. I heard none of it. The mailman came.
From the closing table
Deals that close on schedule aren't an accident. These are the people who lived it, in their own words, from Google, Zillow, Facebook and Experience.com.
One move this week
Send this to the one person you thought of while reading it.
You have somebody in mind. The client who went quiet, the sibling who keeps saying next year, the coworker who brought up rates at lunch on Thursday. Same move for all four of you: pass it along before Monday.
"You probably saw the Fed raised rates Wednesday. That is the bank-to-bank rate, not mortgage rates, and the two do not always move together. Worth reading before you decide anything. And if you want your actual payment at today's pricing, I know the guy."
That message does three things at once. It tells them you were thinking about them on a Wednesday night, it corrects the thing they got wrong without making them feel dumb, and it ends somewhere they can say yes to.
Send the yeses to me. Same-day numbers back at current pricing, plus the purchase price that holds the payment where it needs to be. No application and no credit pull to get that conversation started.
If the news made somebody nervous this week, whether that is your client, your brother-in-law or you, forward my number along or just send me the question yourself. Happy to be the one who explains it so nobody has to guess.
Brian Marchand