Home  /  Areas Served  /  Albany, NY
Albany, New York

Albany, NY.

The lender who actually answers - and gets it closed. From first-time buyers to refinances across the Capital Region, Brian Marchand makes the mortgage the easy part.

5.0★ average rating
169 verified reviews
Local to the Capital Region
Answers days, nights & weekends
Before you dig in — a word from Brian
“Two houses on the same street in Albany can finance completely differently. The program you choose decides which one closes.”
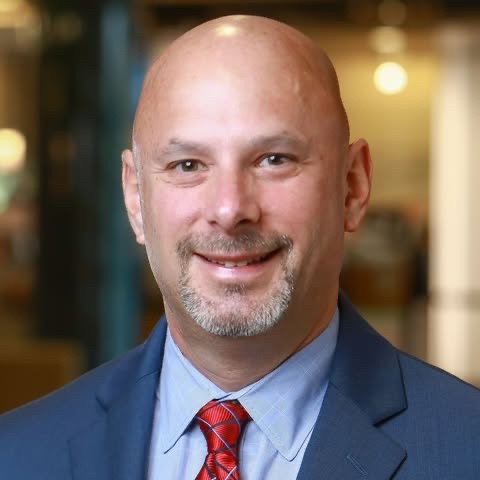
Brian Marchand Brian MarchandSr. Loan Consultant · NMLS #481563

Program guidelines on this page last verified . Guidelines, limits and program terms change — verified figures are current as of that date, not a commitment to lend.

Who you're actually working with

A former Realtor who
now handles the loan.

NMLS #481563

Licensed mortgage lending through New American Funding.

Nearly 1,000 closings

Home sales Brian closed as a Realtor before he ever wrote a mortgage.

In lending since 2008

Started in Capital Region real estate in 1993, so he knows this market cold.

169 reviews

A five-star average from clients across Google, Zillow, Facebook and Experience.com.

Nights and weekends

Offers don't wait for business hours, so Brian doesn't either. Call or text.

Equal Housing Lender

New American Funding, LLC · NMLS #6606. Serving Albany and the Capital Region.

Your Albany loan consultant

Home financing,
the way it should be

Buying or refinancing a home in Albany shouldn't mean chasing down a lender who never calls back. Brian Marchand has spent years helping buyers across the Capital Region - from first-time buyers near Washington Park to homeowners refinancing in the suburbs.

What Albany clients say again and again is simple: he answers. Text him on a Saturday, call him after hours, ask the "silly" first-timer question - you'll get a real answer, quickly, in plain English.

And when a file is tricky, that's exactly when Brian does his best work. Second opinions welcome.

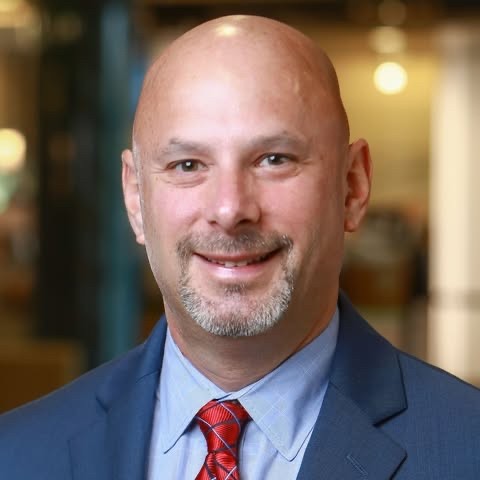
Brian Marchand, mortgage loan consultant serving Albany, NY
Getting to know Albany

A snapshot of
Albany, NY

99,000Population
$310KMedian list price, July 2026
23Median days to contract

New York's capital and the economic heart of the region, a walkable city of historic brownstones, tree-lined parkways and a state-government job base that holds steady through national swings. Buyers range from young professionals near downtown to families in the quieter western neighborhoods. Housing stock skews older than the suburbs, which matters more for financing than most people expect.

Neighborhoods & areas: Pine Hills · Center Square · Buckingham Lake · Delaware Ave · New Scotland

Population is a U.S. Census / ACS estimate. Median list price and median days to contract reflect third-party aggregated Albany data for July 2026. For general reference only.

Worth knowing

What to know about
buying in Albany

The school districts, the programs that can shrink your out-of-pocket, and the details worth handling before you make an offer.

School districts

Albany is served primarily by the City School District of Albany, and the school line is typically 60% to 70% of the total bill. Districts across Albany County vary in rate by 30% to 50%, so the exact lines get confirmed for a specific address before an offer goes out.

You may not need 20% down

Brian works with 3% & 5%-down conventional, FHA (3.5% down), zero-down VA, plus USDA in the rural stretches of Albany County, and SONYMA first-time-buyer loans with down-payment assistance. First-time buyer? See every Albany first-time buyer program, including local help that stacks with SONYMA.

See loan programs →
Loan programs for Albany

The right program depends on
the house and the file

There's no single best loan in Albany. The one that fits comes down to the property, your credit and how much you're putting down. Here's how the programs Brian runs every week actually play out in this market.

3% to 5% down

Conventional

Best for stronger credit and older homes

Conventional financing is the most forgiving on a home's condition, which matters a lot on Albany's older housing stock. If you're eyeing a Pine Hills rowhouse or a Center Square place that needs a little love, this program often clears an appraisal that a government loan would flag.

See conventional details →
3.5% down

FHA

Best for lower down payment or thinner credit

FHA opens the door with less down and more flexible credit. The trade is minimum property standards, so on a pre-1978 Albany home an appraiser can flag peeling paint, an aging roof or a safety item as a condition of closing. Knowing that before you write the offer keeps it from becoming a surprise.

See FHA details →
Zero down

VA

Best for veterans and active service members

If you've earned it, VA is one of the strongest loans out there: no down payment and no monthly mortgage insurance. It follows property standards like FHA does, so the same condition notes apply on older Capital Region homes. Worth structuring early so your offer stays competitive.

See VA details →
Zero down

USDA

Best for the rural edges of the county

USDA offers zero down, but the geography is the catch. It's available in the rural stretches of Albany County, not inside the city itself. If you're looking out toward the county's edges, it's worth checking your address against the map before you rule it out.

See USDA details →
First-time buyers

SONYMA

Best when the down payment is the hurdle

New York's own first-time-buyer program pairs a competitive loan with down payment assistance, and New American Funding is a participating lender. At Albany's price point, that assistance can be the difference between watching from the sidelines and getting into your first home this year.

See SONYMA details →
Buy and fix in one loan

Renovation financing

Best for a home that needs work before it's right

This is Brian's wheelhouse. FHA 203k and HomeStyle renovation loans let you roll the repairs into the mortgage, so a dated kitchen or a fixer on a great Albany block becomes possible instead of impossible. On a two-to-four family, a portion of the rent can often help you qualify too.

See renovation details →
How it works

Getting a mortgage in Albany,
start to keys

If you've never done this before, the process can feel like a black box. It isn't. Here's the whole path, and the few spots where Albany specifically trips people up.

01

Get pre-approved first

Before you tour a single home, we figure out what you can actually buy - often same day or next.

02

Shop with the right program in mind

Albany homes go to contract in a median of about 23 days, so you want to move fast and clean. Because Brian was a Realtor first, we match the loan to the house up front instead of fighting the appraisal later.

03

Make the offer and apply

Once you're under contract, we turn the pre-approval into a full application. If it's a two-to-four family, this is where we build in the rent schedule so a portion of the market rent can help you qualify.

04

Appraisal and inspection

The lender orders the appraisal to confirm value and, on government loans, condition. This is the step Albany's older housing stock can complicate, so if a pre-1978 home flags peeling paint or a safety item, we've usually seen it coming.

05

Underwriting

Tough files are where experience earns its keep, so if something's complicated we sort it here rather than at the closing table.

06

Clear to close, then keys

Once you're cleared to close, we walk through the final numbers together, you sign, and the home is yours. No surprises at the table, because we handled the surprises weeks earlier.

Local detail that changes the loan

On the ground
in Albany

One city, very different neighborhoods — and the loan that works in Pine Hills is not always the one that works in Helderberg.

Neighborhoods behave like separate markets

Pine Hills, the Mansion District, Helderberg, New Scotland Avenue and the West End differ in housing type, condition and price far more than the city-wide numbers suggest. Two-family stock is concentrated in some neighborhoods and nearly absent in others, and that changes which qualifying strategy is even available to you.

The student-rental investor market

Proximity to UAlbany, Saint Rose and the medical college supports a real rental market, which means investor purchases come up constantly here. An investment property is a different underwrite: more down, different pricing, and either personal-income qualifying or a DSCR approach where the property's rent covers its own payment instead of your tax returns.

City assessment and exemptions

Albany's assessment and exemption picture is its own conversation, and the seller's exemptions never transfer to you. A listing's tax figure that reflected a senior, veterans or clergy exemption will be higher for you. Register your STAR credit with New York State after closing — nothing happens automatically.

Condition varies block to block

Much of the city's housing is pre-1978, and on FHA or VA that means peeling paint, aging roofs and health-and-safety items become repair conditions. A block with recent investment and a block without can produce very different repair lists on similar houses. Conventional is more forgiving, and renovation financing can fold the work into the purchase.

From Albany clients

Real Albany buyers.
Real results.

★★★★★
Everyone was so friendly, helpful, and professional! We really appreciated the fast and clear communication. The entire process went smoothly from the beginning to the end.
MMichael C.
Albany, NY
★★★★★
From pre-approval to finalizing our mortgage, Brian consistently made us feel like a priority. Every time we reached out he got back to us in less than two days.
CCaitlin
Albany, NY · Zillow
★★★★★
As a first-time buyer I was clueless about the process, and it was especially tough during the pandemic. Brian was extremely helpful to me as a newbie.
SSinan C.
Albany, NY · Zillow
★★★★★
I highly recommend Brian. He consistently provides a five-star mortgage experience for my clients - quick response time, strong communication, and in-depth knowledge.
GGenevieve S.
Albany, NY · Real estate partner
★★★★★
Brian pre-qualified me and my wife for our new home after helping us three years ago for our first. A must-use in the Capital District.
JJohn G.
Albany, NY · Zillow
★★★★★
Brian was responsive and kept me in the loop throughout. I'm really glad I had such a great experience.
KKirsten R.
Albany, NY

Verified reviews from Google, Zillow, Facebook & Experience.com · See all 169 reviews →

In & around Albany

Albany County,
town by town

Type in your address to see the real driving distance and time from your doorstep to every town we serve nearby.

Drive times to each town

Enter your address to see the real driving distance and time to every town we serve nearby.

Sorted by drive time - closest first. Tap a town to find it on the map.

Estimates via OpenStreetMap routing - typical driving times, not live traffic.
Good to know

Albany mortgage
questions, answered

Does Albany's older housing stock cause appraisal problems?+
It can, and it's worth knowing before you write an offer. Government-backed loans like FHA and VA follow minimum property standards, so an appraiser flagging peeling paint on a pre-1978 home, an aging roof, or a health-and-safety item will make those repairs a condition of closing. Conventional financing is generally more forgiving on condition. On a historic Albany rowhouse, the loan program you choose can decide whether a repair list becomes a delay or a non-issue.
Can rental income from a two-family help me qualify?+
Often yes. Albany has a meaningful supply of two-to-four unit properties, and on an owner-occupied purchase a portion of the market rent can typically be counted toward qualifying income. The appraiser has to complete a rent schedule to support it, and the percentage that counts varies by loan program. It's one of the more effective ways to buy in this city with a modest income, and it's worth structuring deliberately rather than discovering late.
How fast can I get pre-approved?+
Often the same day or the next. You can start your pre-approval online anytime, or book a quick call with Brian. With Albany homes going to contract in a median of about 23 days, a real pre-approval is what lets you move when the right one shows up.
What loan programs work best in Albany?+
It depends on the property and the file. Conventional 3% and 5% down, FHA at 3.5%, zero-down VA, and SONYMA first-time-buyer loans with down payment assistance all get used here regularly. USDA is available in the rural stretches of Albany County but not in the city itself. Renovation financing is worth a look on older homes that need work. See the full lineup on the Loan Programs page.
Are you actually available on nights and weekends?+
It's the single most common thing clients mention. Homes and offers don't wait for business hours, so Brian doesn't either - call or text and you'll hear back quickly, even after hours.

More answers: 500+ questions on buying in the Capital Region →

Brian Marchand, Sr. Loan Consultant at New American Funding

Brian Marchand · Sr. Loan Consultant, New American Funding · NMLS #481563

Works on mortgages for buyers and homeowners in Albany and the Capital Region. Licensed in New York State. New American Funding, NMLS #6606 · 18 Computer Dr E, Suite 103, Albany, NY 12205.

About Brian