Before you dig in — a word from Brian
“Chatham is where people find the acreage they wanted. Acreage is also where appraisals and well-and-septic get interesting.”
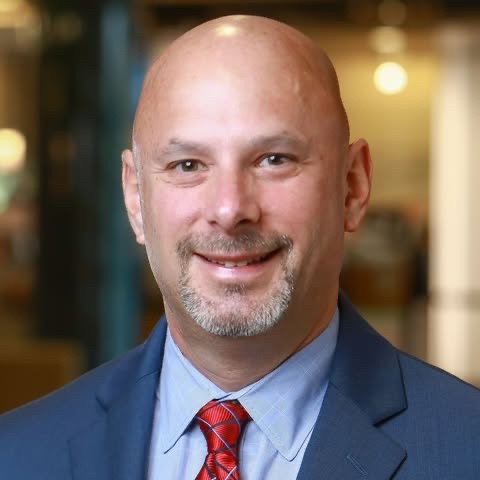 Brian MarchandSr. Loan Consultant · NMLS #481563
The lender who actually answers - and gets it closed. From first-time buyers in the village to farmhouse purchases out on the county roads, Brian Marchand makes the mortgage the easy part.
“Chatham is where people find the acreage they wanted. Acreage is also where appraisals and well-and-septic get interesting.”
Brian MarchandSr. Loan Consultant · NMLS #481563
Buying or refinancing in Chatham shouldn't mean giving up when a file gets complicated. Brian Marchand has helped buyers throughout Columbia County - from first-time buyers in Chatham village to move-up families on land in Ghent and Old Chatham.
This is where Brian's persistence stands out. One local buyer put it simply: the team "worked with me in spite of hurdles to get my loan approved."
Been told "no" somewhere else? That's exactly where Brian goes to work. Yes, when other lenders say no.
A village center, a well-regarded district, and a lot of rural acreage - each one changes a different line of your file.
Columbia's effective rate runs about 1.40%, among the lowest of the counties Brian serves. On a county median value of $347,100 that works out to roughly $405 a month in taxes before principal and interest.
Chatham CSD covers the village and much of the surrounding town, with edge addresses falling toward Ichabod Crane or New Lebanon. School levies typically drive 60% to 70% of a New York tax bill, so the district line moves your payment more than the town line does.
Plenty of Chatham listings come with real land and outbuildings. Conventional appraisals give limited value to acreage beyond the homesite, and barns can be treated as contributory or not at all. If the price assumes the land, the appraisal needs to be discussed before the offer, not after.
A village with a working main street surrounded by farmland and country properties. Popular with Albany commuters who want land, and with second-home buyers priced out of Hudson.
Neighborhoods & areas: Chatham village · Old Chatham · East Chatham · Ghent
Population is a 2020 U.S. Census figure for Chatham. Home value, household income and the effective rate are Columbia County U.S. Census / ACS estimates; town, village and school district figures vary. For general reference only.
Beyond the sticker price - the monthly math, local property taxes, the school districts and the programs that can shrink your out-of-pocket.
*Escrow illustration only. Taxes and insurance estimated against the Columbia County median value of $347,100; your actual assessment, exemptions and premium will differ. Principal and interest are not shown here because they depend on your credit, loan program, down payment and market conditions on the day you lock — use the calculator or call me for real numbers. Not a commitment to lend. Equal Housing Lender.
Chatham sits in Columbia County, where effective rates run about 1.40%. Against the county median value of $347,100 that is roughly $405 a month before principal and interest. STAR and veterans credits can reduce it.
The village and most of the town are served by Chatham Central School District, with edge addresses falling toward Ichabod Crane or New Lebanon. Because school levies typically account for 60% to 70% of a New York tax bill, the district gets confirmed for the exact address before an offer goes out.
Brian works with 3% & 5%-down conventional, FHA (3.5% down), zero-down VA, plus USDA across much of Columbia County, and SONYMA first-time-buyer loans with down-payment assistance. First-time buyer? He'll line up every credit you're eligible for.
Brian and his team were awesome and really helped me with a pretty complicated process. Can’t recommend them enough!
Brian explained everything well, was very thorough, and always answered my questions quickly. I would recommend him to everyone.
I highly recommend Brian. He consistently provides a five-star mortgage experience for my clients - quick response and deep knowledge.
Verified reviews from Google & Zillow · See all 166+ reviews →
Type in your address to see the real driving distance and time from your doorstep to every town we serve nearby.
Enter your address to see the real driving distance and time to every town we serve nearby.
Sorted by drive time - closest first. Tap a town to find it on the map.