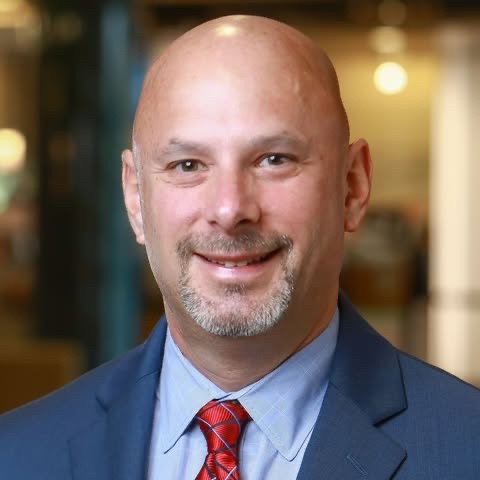
Every rate you see online belongs to a specific borrower: excellent credit, a big down payment, a single-family primary residence, a conforming loan amount, and a 30-day lock. Change any one of those and the number changes. Rather than post a rate that won't be yours — or accurate by tomorrow — I'd rather show you exactly how yours gets built, so nobody can sell you a number you don't understand.
“Anybody can quote you a low rate. The question is whether they can close it — and what it costs in points to get there. Ask for the rate and the credit or cost attached to it, in writing, every time.”
Brian MarchandSr. Loan Consultant · NMLS #481563
Mortgage pricing starts from a base and gets adjusted for risk. Understanding the four biggest levers puts you in control of a number most buyers treat as fixed.
Pricing moves in tiers, not smoothly. Going from 719 to 720 can matter more than 740 to 780. Sometimes a small, targeted fix pays for itself many times over.
Loan-to-value bands adjust pricing. Getting under a threshold — or above it — is often worth more than negotiating.
You can buy the rate down by paying points, or take a higher rate for a lender credit toward closing costs. Neither is better; it depends on how long you’ll hold the loan.
FHA, VA, conventional, jumbo and portfolio all price on different curves. The cheapest rate and the cheapest loan are frequently not the same program.
In roughly the order they matter. Six of the seven are things we can work on together before you lock.
The largest single adjustment on most files, and the one most worth improving before you shop. Credit game plan.
How much you put down, or how much equity you have on a refinance. Threshold-driven, not linear.
Government-backed loans price differently than conventional, and portfolio loans differently again. Compare programs.
A primary single-family prices best. Second homes, investment properties, 2-4 units, condos and manufactured homes each carry adjustments.
Very small loans and amounts above the conforming limit both price differently. Jumbo loans.
A 30-day lock costs less than a 60- or 90-day lock. On new construction, the lock strategy is a real part of the cost. Construction loans.
The only factor nobody controls. Mortgage pricing tracks mortgage-backed securities and can move more than once in a single day.
Locking is a decision with a cost either way. Here's how I make it with clients instead of for them.
Your actual credit tier, LTV, program, occupancy and lock period — not a rate-sheet headline. You get the number and what it costs.
Par rate, one point down, and a lender-credit option. With the break-even month for each, so the choice is arithmetic rather than instinct.
We lock when it protects you — usually once you’re under contract with a firm closing date. I’ll tell you what a float-down is available for and what it costs.
If the market improves meaningfully later, refinancing is a conversation I’ll start with you rather than wait for you to ask. Homebot tracks it monthly.
Direction and rough magnitude only — actual adjustments change with the market and by program. This is to show you where the leverage is, not to quote you.
| Factor | Better rate | Worse rate | Can we change it? |
|---|---|---|---|
| Credit score | Higher tier | Lower tier | Often, and it’s the biggest lever — sometimes in 30-60 days |
| Down payment / LTV | More equity | Less equity | Sometimes — crossing a threshold can be worth more than the extra cash |
| Occupancy | Primary residence | Second home, then investment | Only if your plan genuinely changes |
| Property type | Single-family detached | Condo, 2-4 unit, manufactured | No — but it changes which program is cheapest |
| Loan program | Depends entirely on your file | Depends entirely on your file | Yes — this is the real work |
| Points paid | Points paid up front | Lender credit taken | Yes — your choice, based on how long you’ll hold it |
| Lock period | Shorter lock | Longer lock or an extension | Yes — with a realistic closing timeline |
| Loan amount | Conforming range | Below minimum or above the limit | Sometimes, with the down payment |
| Market conditions | Bond market rallies | Bond market sells off | No — which is why timing the lock matters |
Some of the most common advice in this business is wrong, and a couple of these actively cost people money. Worth knowing before you shop.
Rate sheets across lenders are far closer than people assume — they price off the same securities. What differs is execution, program access, and whether the quote survives underwriting. Two quotes is diligence; six is noise.
Talk to Brian →A rate quoted with two points attached isn't the same product as a rate quoted at par. Always ask for the rate and the points or credit together, in writing. It's the only way to compare.
Talk it through →Credit changes take a cycle to report, and paying a collection can re-age it and drop your score. If we're improving credit for pricing, we do it deliberately and with timing.
Credit game plan →LTV adjustments are threshold-based. Going from 12% to 15% down may do nothing at all, while 3% more might cross a band. Know where the line is before you drain your savings.
Run the numbers →Pre-approval costs nothing and doesn't lock anything. Being ready when the market moves is the whole advantage — buyers who wait to start are the ones who miss it.
Get pre-approved →Points only pay off if you hold the loan past the break-even month. If the plan is to refinance in two or three years — as it often is on FHA or portfolio loans — taking the credit instead is usually the better trade.
Compare programs →A quote is a promise about a file nobody has underwritten yet. These are the six ways the number you were told stops being the number you get.
A rate quoted off an estimate or an app score. The tri-merge comes back a tier lower and the pricing changes — usually discovered at lock.
I price off your actual pulled credit, not an estimate. If you're one tier from a better bracket, I'll tell you what it would take and whether it's worth doing first.
A headline rate that required two points. The borrower compares it to a par quote from someone else and picks the wrong loan.
Every quote I give shows the rate and the cost or credit attached to it. If someone else quoted you lower, send me their figures and I'll show you what's actually in them.
A 30-day lock on a 45-day closing. An extension costs money, and in a rising market it costs real money.
I set the lock period against a realistic closing date for your program — including the extra time SONYMA, USDA and construction files genuinely need.
Quoted as a primary single-family, but it's a condo, a 2-4 unit, or a second home. Each carries an adjustment that wasn't in the original number.
I price the actual property and occupancy from the start, which means my quote holds when the appraisal confirms what the property really is.
The file starts conventional, credit or DTI doesn't support it, and it moves to FHA — a different rate and a different mortgage insurance structure entirely.
I pick the right program at pre-approval rather than defaulting to conventional and pivoting under pressure. Fewer surprises, and a quote that survives.
Rates can move more than once in a day. An unlocked quote from last Tuesday is a historical fact, not an offer.
I tell you plainly when a quote is floating versus locked, and we make the lock decision together with the market in front of us.
Already been denied somewhere else? Here's how I take over a dead file →
Because it would be wrong by tomorrow and wrong for most of the people reading it. Mortgage pricing moves daily — sometimes intraday — and the rate that applies to you depends on your credit tier, down payment, program, occupancy, property type, loan amount and lock period. A posted number is marketing. A quote on your actual file is information. Ask me for the second one.
It depends on one thing: how long you’ll keep the loan. Points have a break-even month — the point at which the monthly savings exceed what you paid up front. Hold the loan past it and you win; refinance or sell before it and you lost money. I’ll show you the break-even for each option so it’s arithmetic, not a sales pitch.
More than any other factor you control. And because pricing moves in tiers, the effect is lumpy — landing one point below a threshold can cost you meaningfully, while a 40-point improvement inside the same tier may change nothing. That’s why I look at where you sit relative to the brackets before recommending any credit work. Here’s the approach.
Usually once you’re under contract with a firm closing date — that’s when a lock protects something real. Locking before you have a property means paying for a lock period you may not use. If you’re locked and the market improves significantly, ask about a float-down; whether one is available and what it costs varies by program.
Less than the marketing suggests — everyone prices off the same mortgage-backed securities. What genuinely differs is program access, underwriting overlays, and execution. A slightly better rate at a lender that can’t close your file is worth nothing, and a lender without the right program will decline you at any rate.
Nobody can answer that honestly, including me — and anybody who tells you they can is guessing. What I can tell you is the math: get pre-approved now, because it costs nothing and locks nothing, and you’ll be ready when your moment comes. Buyers who wait to start the process are the ones who miss the window, not the ones who wait to buy.
The rate determines your payment. APR is a federally required figure that folds certain costs into a single annualized percentage so loans can be compared. APR is useful but imperfect — it assumes you hold the loan to term, which most people don’t. Compare the rate, the points or credit, and the total closing costs. That’s the real comparison.
Almost always one of four things: your credit tier, your loan-to-value, your occupancy or property type, or points baked into the advertised number. Send me the advertisement and your quote and I’ll show you exactly which one it is. If your quote is genuinely off market, I’ll tell you that too.
Licensed across New York State — with deep roots in Albany and the Capital Region.
Don't see your town? Reach out — or see every Capital Region town.
This page is educational and does not quote or offer a specific interest rate, annual percentage rate, or loan term. Mortgage rates change daily and are determined by your individual credit profile, loan-to-value, loan program, occupancy, property type, loan amount, lock period and market conditions at the time of lock. All loans are subject to credit approval, income verification and property appraisal. Rates and terms are not guaranteed until locked in writing. Brian Marchand, NMLS #481563 · New American Funding. Equal Housing Opportunity.