Refinancing is arithmetic, not opinion. When it pays, when it does not, and how to tell the difference before someone quotes you a rate.
Before the mortgage side, I sold over 1,000 homes here in the Capital District. These answers come from someone who has sat in the agent’s chair at the closing table — not a banker reading you a policy manual.
It turns almost entirely on your current first-mortgage rate. If you are sitting below market, a cash-out refinance reprices your whole balance to access a slice of it — usually a bad trade. If your current rate is at or above market, the refinance can win outright. I run both and show you the total cost of each.
Full breakdown: HELOC & home equity →
#Take your appraised value, multiply by the program maximum — commonly 80–85%, sometimes 90% — and subtract what you still owe. A $500,000 home at 85% is $425,000; if you owe $300,000, your ceiling is roughly $125,000.
Full breakdown: HELOC & home equity →
#A HELOC is a revolving line you draw from as needed, usually at a variable rate, with a 10-year draw period. A home equity loan is a fixed-rate lump sum with a set payment from day one. Lines suit costs that arrive in stages; loans suit a known number you want locked.
Full breakdown: HELOC & home equity →
#On most programs, no — an undrawn line carries no monthly payment. Check for annual fees and early-closure fees, which some lenders charge if you close the line within the first couple of years. That is a question worth asking before you sign.
Full breakdown: HELOC & home equity →
#On a limited number of programs, yes, though the CLTV limits are lower and pricing is higher than on a primary residence. If the goal is pulling capital out of a rental, also price a DSCR cash-out refinance — it often works out better.
Full breakdown: HELOC & home equity →
#Interest on home equity debt may be deductible when the funds are used to buy, build, or substantially improve the home securing the loan — not when used for other purposes. I am not a tax advisor; confirm your situation with your CPA before counting on it.
Full breakdown: HELOC & home equity →
#Commonly two to three weeks. Second-position files are lighter than a full refinance, and many programs accept an automated or drive-by valuation instead of a full interior appraisal.
Full breakdown: HELOC & home equity →
#A HELOC is usually cheaper up front, with lower closing costs and interest charged only on what you draw. A cash-out refinance can be cheaper over the long run if your existing rate is already high, because you consolidate everything at one fixed rate. If your current first mortgage rate is low, the HELOC almost always wins on total cost, since a refinance would re-price your entire balance.
Full breakdown: HELOC vs. cash-out refi →
#No. A HELOC is a separate loan in second position behind your first mortgage. Your existing rate, term and monthly payment stay exactly as they are. That is the main reason homeowners with low pandemic-era rates choose a line over a refinance.
Full breakdown: HELOC vs. cash-out refi →
#A HELOC commonly allows borrowing up to roughly 85% of your home value including the existing first mortgage balance, while a conventional cash-out refinance typically caps at 80% loan-to-value. Both depend on credit, income and property type, and limits vary by lender.
Full breakdown: HELOC vs. cash-out refi →
#Most HELOCs carry a variable rate tied to an index, meaning the payment can change over time. Some lenders offer a fixed-rate option on individual draws, which converts a portion of the balance to a set rate. A cash-out refinance is typically fixed for the life of the loan.
Full breakdown: HELOC vs. cash-out refi →
#A HELOC often closes in about two to three weeks. A cash-out refinance generally takes 30 to 45 days because it involves full underwriting of a new first mortgage, a full appraisal and a new title policy. Timelines vary with appraisal availability and how quickly documentation comes in.
Full breakdown: HELOC vs. cash-out refi →
#Yes, both are commonly used to access equity for a purchase, and it is one of the main strategies for buying before selling. Which one fits depends on your existing rate and whether you intend to pay the balance back from the sale proceeds. There are also bridge options worth comparing.
Full breakdown: HELOC vs. cash-out refi →
#When it changes something real: a lower payment you will keep long enough to recover the costs, dropping mortgage insurance, getting out of an adjustable rate, consolidating high-interest debt, or pulling cash for a specific purpose. Not because a mailer told you to.
#Typically a few thousand dollars in title, recording, appraisal and lender fees, and in New York the tax side matters too. The real question is not the cost — it is how many months it takes to earn it back. I will show you that number.
#There is no magic number, and anyone who quotes you one is guessing. A big balance can justify a small drop; a small balance needs a bigger one. Breakeven math beats rules of thumb.
#Sooner than most people expect. Rate-and-term refinances often have no seasoning requirement, and cash-out typically requires six to twelve months depending on the program. If you bought at a high rate, it is worth an annual check-in.
#Yes, and that increase is usually the whole opportunity — it can drop your mortgage insurance, improve your pricing tier, or open up cash-out. Try the refinance calculator and send me the numbers.
#Often, yes. FHA and VA streamline options are less credit-sensitive, and portfolio programs exist for scores conventional will not touch. Whether it is worth doing is a separate question — and I will answer that one honestly.
#Sometimes. FHA and VA streamlines can work with minimal equity, and some conventional options go to high loan-to-value on a rate-and-term basis. Cash-out is where equity becomes non-negotiable.
#Yes, once you are past the program’s waiting period — generally two years for FHA and VA after a Chapter 7 discharge, four for conventional, with shorter paths in documented circumstances. Non-QM options can be earlier still.
#Yes, and it is one of the most valuable refinances there is, because it ends FHA mortgage insurance that otherwise lasts the life of the loan. You generally need about 20% equity to make it worthwhile.
#Yes, if your equity supports it. On conventional loans you may not even need a refinance — PMI can often be removed by request or appraisal. On FHA, a refinance is usually the only exit.
#Both, and both are legitimate. Shortening saves an enormous amount of interest if the payment fits. Lengthening lowers the payment when cash flow matters more than the payoff date. It is your call, with real numbers in front of you.
#Yes — that is a cash-out refinance, one loan that replaces your mortgage and hands you the difference. Pricing is slightly higher than rate-and-term, and most programs cap you around 80% of value.
#Sometimes it is the smartest thing you can do, and sometimes it just moves the problem and adds thirty years to it. The math has to work and the cards have to stay paid off. I will say plainly which situation I think you are in.
#A new 30-year term does reset the amortization clock, which is why a lower payment is not automatically a win. You can refinance into a shorter term, or keep the new payment and pay extra toward principal.
#Tapping equity is often the smartest, cheapest move available to a homeowner. It's also the easiest way to turn short-term spending into a thirty-year problem. Here's when I'd tell you not to.
You’d be borrowing to cover a shortfall you can’t fix. If income doesn’t cover your obligations, a HELOC postpones the problem and adds a lien to your house. That’s a conversation about cash flow, not a loan. Talk to Brian →
Your first mortgage rate is low and you need a large amount. Don’t refinance a 3% first mortgage to access equity. A second lien keeps the low rate intact. The reverse is also true — if your first mortgage rate is high, a cash-out refi may beat a HELOC. HELOC vs cash-out refinance →
You want payment certainty and a variable rate scares you. A HELOC is a variable-rate line. If a rising payment would keep you up at night, take a fixed-rate home equity loan or a cash-out refinance instead. Compare the options →
You have under about 15-20% equity. Combined loan-to-value limits are real. On most programs you need to keep 15-20% equity in the home after the new line, which means a recent purchase often has nothing to draw on yet. Check your value →
You’re about to sell. A new line costs money to set up and many carry early-closure fees. If the house is going on the market within a year, it’s rarely worth it. Buying before selling →
You’re funding a full renovation on a house you just bought. A renovation loan rolled into your purchase financing is usually cheaper and lends against the after-improved value — which a HELOC won’t do. Renovation loans →
Full breakdown: HELOC & home equity →
#Second-lien underwriting is generally lighter than a first mortgage, but income still has to support the combined payment. Here's what counts.
Counts toward qualifying: W-2 wages — Paystubs and W-2s, often with lighter documentation than a purchase requires. Self-employment income — Two years of returns. Some lenders offer bank statement HELOCs for self-employed owners. Retirement, pension, Social Security, disability — Documented and continuing, grossed up when non-taxable. Very common on equity files. Rental income from properties you own — Leases and Schedule E history. Bonus, overtime, and commission — Two-year average where the history supports it. Asset-based qualification — Some lenders will qualify a large line on assets rather than income — useful for retirees with equity and a portfolio.
Doesn't count (or counts against you): Income that ignores the new payment — The draw creates a payment. On a variable line, underwriting stresses it at a higher rate than today’s — so plan on the stressed number. The money you’re about to borrow — Borrowed funds aren’t income, and using a HELOC draw as the down payment on another property has its own disclosure rules. Business income from an entity you can’t document — Same two-year and ownership-documentation standards as any other loan. A tenant you hope to place — Projected rent without a lease generally isn’t usable on a second lien. Tax deductibility you’re assuming — Interest is deductible only when proceeds are used to buy, build, or substantially improve the home — and only within limits. Ask your accountant, not your loan officer.
A HELOC on your primary to buy an investment property is a legitimate and common strategy — pair it with a DSCR loan on the purchase and you can scale without touching your DTI.
Full breakdown: HELOC & home equity →
#Equity lending gets declined over value, lien position, and title far more than over income.
The valuation comes in lower than expected. The homeowner used an online estimate and the appraisal or AVM lands lower, wiping out the available equity at the CLTV limit. What I do: I look at real comparable sales in your specific neighborhood before we apply, and I know when a full appraisal will beat an automated valuation on an improved or unusual property.
Combined loan-to-value exceeds the limit. The first mortgage balance plus the requested line exceeds what the program allows. Homeowners forget the first mortgage counts. What I do: I calculate your actual available line from the current payoff and the realistic value, so the number I quote is the number you can get.
Title problems. An old lien that was never released, a judgment, unpaid taxes, a contractor's mechanic's lien, or a deed issue from a divorce or inheritance. Second liens surface these constantly. What I do: We run title early. Released-but-unrecorded liens and stale judgments take time to clear, and starting in week one means they don't become the reason you miss a deadline.
Insufficient equity because of a recent purchase. A homeowner who bought last year with 5% down has nothing to draw on, regardless of how much the market has moved. What I do: I'll tell you honestly whether you have room. If you don't yet, I'll tell you roughly when you will — and I'd rather say that than run a pointless application.
Property type or occupancy restrictions. Many HELOC lenders won't touch investment properties, second homes, condos, or manufactured housing. The homeowner qualifies and the property doesn't. What I do: I match the property type to a lender who actually lends on it. Investment-property HELOCs exist; they're just not offered by everyone.
DTI with the stressed payment. The line is approved against a stressed rate, not today's rate. A file that works at the current index fails at the stress test. What I do: I underwrite you at the stressed payment from the start. If the full line doesn't work, we size a smaller line that does rather than getting a decline.
Full breakdown: HELOC & home equity →
#Fifteen minutes, no credit pull, no application, no pitch. Worst case you learn something and I don’t get your business.
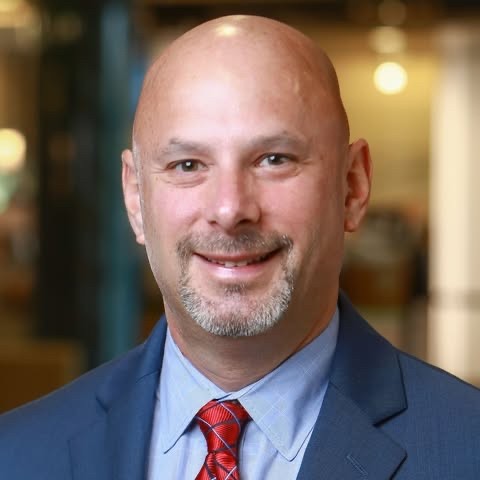
Brian Marchand · Sr. Loan Consultant, New American Funding · NMLS #481563
Works on refinancing and home equity for buyers and homeowners in Albany, NY and the Capital Region. Licensed in New York State. New American Funding, NMLS #6606 · 18 Computer Dr E, Suite 103, Albany, NY 12205.