Home  /  Q&A  /  Deals other lenders won’t touch
20 questions answered

Deals other lenders won’t touch

These are the files that get declined somewhere else and land on my desk. A denial almost never means the loan is impossible — it usually means that lender ran out of programs. Here is what actually happens with the hard ones.

Before the mortgage side, I sold over 1,000 homes here in the Capital District. These answers come from someone who has sat in the agent’s chair at the closing table — not a banker reading you a policy manual.

Every lender I've talked to said no. Is one more call worth it?

Yes, and bring the denial letter. A “no” almost never means the loan is impossible — it means that lender's shelf ran out. Most banks carry five or six programs. Between FHA for scores as low as 500 (10% down under 580), bank statement, ITIN, foreign national, DSCR, asset depletion and the rest of the Non-QM shelf, I'm working from a much longer list.

I'll also tell you straight if the answer really is “not yet,” and exactly what would have to change. The only file I can't help with is the one I never see. Here's how some of those turned out.

From the Realtor side of the tableAs an agent I lost deals to lenders who said no on a Thursday and never explained why. Here you get the reason, in plain language, plus the list of what would have to change.
#
My lender just dropped my loan a week before closing. Can you save it?

Sometimes, and it depends entirely on why. If the problem is the property — appraisal, condition, a condo project that failed review — a different program often fixes it fast. If the problem is the borrower, we restructure, and that takes longer than a week.

First call: tell me what they told you, and send the last document they asked for. Then I'll tell you whether this is a rescue or a rebuild — not a hopeful yes to win the file and an apology on closing day.

From the Realtor side of the tableI have been the agent making the extension call to a listing agent, and I know exactly how much credibility it costs you. If it can be saved, it gets saved fast. If it cannot, you deserve to hear that today, not Friday.
#
The appraisal came in under the purchase price. Now what?

A low appraisal isn't automatically a dead deal. There are four real moves: renegotiate the price, bring the difference in cash, file a formal reconsideration of value with better comparable sales, or restructure the loan so the lower value still works.

What you do not do is panic and cancel on day one. We look at the comps the appraiser actually used first — sometimes they missed a sale two streets over.

From the Realtor side of the tableI have built the reconsideration packet from the agent's side more than once. Appraisers respond to comparable sales, not to outrage. A tight comp set gets a second look; an angry email gets filed.
#
Can I still be denied after I was already pre-approved?

Yes, and here is the honest list of what does it: financing a car or a couch mid-process, changing jobs, an undisclosed debt surfacing on the final credit refresh, a large deposit with no paper trail, a property or condo project that fails review, or a program guideline that moves under you.

Almost all of it is preventable. Between pre-approval and closing, the rule is boring on purpose: no new credit, no job changes, no unexplained deposits, no emptying the account you documented.

#
The house has an underground oil tank. Is the loan dead?

Usually not, but it has to be handled and not hoped away. Underwriting cares about environmental risk and whether the home is insurable. Typical paths: the seller decommissions or removes the tank, a holdback is escrowed for the work, or a tank test and soil report clears it.

These are everywhere in older Capital District housing stock. The ones that close are the ones where somebody raised it before the offer.

From the Realtor side of the tableI have closed plenty of these. The deal dies when the tank turns up at the appraisal. It survives when it is on the table during negotiation, where it belongs.
#
The addition was never permitted and there's no certificate of occupancy.

Very common on older homes here, and very solvable if we start early. The appraiser has to report whether the addition is legal, legal non-conforming, or illegal. Conventional financing can sometimes value it as-is; FHA and VA are stricter, and some towns want the permit closed before they will issue a CO.

The timeline, not the rule, is what kills these. A permit that takes six weeks to close does not fit inside a 30-day contract nobody warned about.

From the Realtor side of the tableThis is one I check before an offer goes in, because an unpermitted third bedroom that the appraiser will not count can change both your value and your loan amount.
#
The septic failed, or the well test came back bad.

On FHA, VA and USDA loans, water potability and septic clearance are requirements, not suggestions. Options: the seller repairs it, funds are escrowed to repair it after closing where the program allows, or renovation financing pays for a whole new system and rolls it into the loan.

That last one is the move most buyers never hear about — a failed septic can be the reason a good house is cheap.

#
It's on a private road or a shared driveway.

Financeable, and mostly a paperwork exercise. Underwriting wants proof of legal, permanent access to the property, and on some programs a recorded maintenance agreement for the road.

It rarely kills a loan. It regularly delays one, because the document usually has to be tracked down from a neighbor or a town clerk.

#
There's an in-law apartment. Does that change the loan?

It depends on whether the second unit is legal and how the appraiser classifies it: a one-unit home with an accessory apartment, or a legitimate two-family. That single line on the appraisal changes your program, your down payment, and sometimes your approval amount.

Worth knowing the upside too — on some programs, rent from an accessory dwelling unit can help you qualify rather than just sitting there as a nice feature.

#
Is it manufactured, modular, or mobile — and does it matter?

Enormously. A modular home is built to the same code as a site-built house and finances like one. A manufactured home needs its HUD tags, a permanent foundation, and a program that will take it. Anything pre-1976 generally isn't financeable at all.

Listing sheets get this wrong constantly. It is worth confirming before you fall in love, because it decides which programs even exist for the property.

From the Realtor side of the tableListings in this market use these three words interchangeably and they are not interchangeable. I check the HUD data plate or the permit history before we spend anyone's inspection money.
#
The house needs $90,000 of work and nobody will lend on it.

They will — just not with a standard mortgage. Renovation financing (FHA 203k and conventional HomeStyle) lends against the after-improved value, so the loan pays for the roof, the kitchen, the furnace and the new septic as part of the purchase.

One loan, one closing, one payment. This is the single most underused program in the Capital Region.

From the Realtor side of the tableThe listing that has sat 120 days through three price drops because the kitchen is from 1974 is exactly the house a renovation loan turns into instant equity. As an agent, those were my favorite deals.
#
My credit score is in the 500s. Am I wasting your time?

No. FHA guidelines allow scores down to 500 with 10% down, and 580 with 3.5% down — individual lender overlays vary, and that is exactly why the answer differs depending on who you ask.

Sometimes the smarter play is 60 to 90 days of targeted work first, because the payment difference between a 560 and a 620 is real money. That's what the Credit Game Plan is for. Either way, you'll get a number and a plan instead of a brush-off.

#
My tax returns show almost nothing because my accountant is very good at his job.

Welcome, you're most of the self-employed Capital Region. Bank statement loans qualify you on 12 or 24 months of deposits instead of your returns. If your money is in assets rather than income, asset depletion converts a balance sheet into qualifying income.

A lender who says your returns disqualify you is telling you about their product list, not about you.

#
I don't have a Social Security number. Can I still buy?

Yes. ITIN loans are built for buyers who file taxes with an Individual Taxpayer Identification Number, and they don't require citizenship or a green card. Thin credit or no score is workable with alternative history — rent, utilities, phone, insurance.

If you're a non-resident buying here, that's a different product: foreign national financing, qualified on assets and often without US credit at all.

#
I bought a house with cash. Can I pull that money back out?

Often yes, and faster than most people expect. A delayed-financing cash-out can be based on the original purchase price rather than making you wait out a seasoning period — so the cash you used to win the deal goes back in your pocket and gets used again.

Auction buyers, flippers and off-market buyers use this constantly. Timing rules are strict, so the conversation happens before the purchase, not a year later.

From the Realtor side of the tableCash offers win here, and this is the mechanism that lets a normal buyer behave like a cash buyer twice. Also worth a look: NAF Cash, which makes the cash offer for you.
#
I want to buy the next house before I sell this one.

Several ways to do it: qualify carrying both payments, count documented rent from the departing home, pull equity with a HELOC before you list, or use NAF Cash to make a cash offer on the new house and sell the old one after you've moved.

Buying first is how you avoid moving twice and making an offer nobody wants to accept. It just has to be structured deliberately.

From the Realtor side of the tableA contingent offer is the weakest paper in a competitive market, and both of us know a listing agent reads it that way. Fixing that before you tour is worth more than any rate.
#
Can I close in the name of my LLC?

On investment property, yes. DSCR loans qualify on the property's rent rather than your personal income, and LLC or S-corp vesting is standard — you personally guarantee the loan, but title vests in the entity. That is why serious investors use them even when they'd qualify conventionally.

On a primary residence, no — different product, different rules.

Full breakdown: DSCR loans

#
My situation doesn't look like anybody's example. Is there even a program?

Probably. The unusual pile is most of my week: 1099 earners, retirees with assets and no paycheck, buyers two years out of a bankruptcy, non-citizens, investors with ten financed properties, people buying a camp with no year-round road, people buying 40 acres and a barn.

Start with Special Situations or run the Program Finder, then call me and we'll skip the part where you explain it three times.

From the Realtor side of the tableAfter a thousand-plus closings I have seen the weird file often enough to recognize it quickly. That is the whole value: not that I know every guideline, but that I know which door to knock on first.
#
What can I do right now to become mortgage-ready?

Four things, in order: stop opening new credit, get your balances under roughly 30% of their limits, leave your savings alone so it can be documented, and find out your actual number instead of guessing.

Do those for 60 days and the difference in what you qualify for is usually measured in tens of thousands. The Credit Game Plan lays it out, and a 15-minute call tells you which of the four matters most in your case.

#
I have no idea which loan I need. Can you just tell me?

That's the job. You don't need to arrive knowing whether you're an FHA buyer or a HomeReady buyer — you need someone to put two or three real structures side by side with actual payments and let you pick.

The Program Finder gets you close in about two minutes. A 15-minute call gets you the rest, with no credit pull and no application.

#

Didn’t see your question?

Fifteen minutes, no credit pull, no application, no pitch. Worst case you learn something and I don’t get your business.

Keep going

More questions, by topic

Or search all 551 questions →

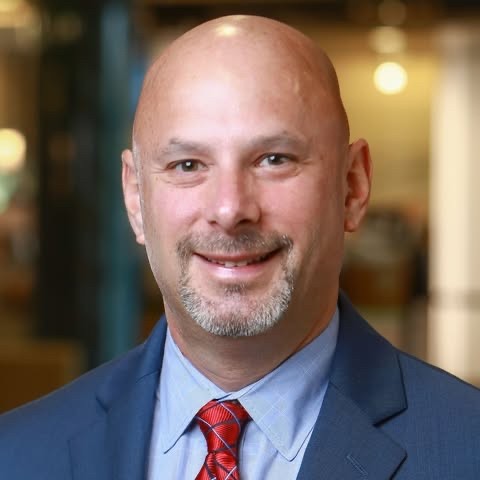
Brian Marchand, Sr. Loan Consultant at New American Funding

Brian Marchand · Sr. Loan Consultant, New American Funding · NMLS #481563

Works on files other lenders have already declined for buyers and homeowners in Albany, NY and the Capital Region. Licensed in New York State. New American Funding, NMLS #6606 · 18 Computer Dr E, Suite 103, Albany, NY 12205.

About Brian