Home  /  Q&A  /  Second homes & investment
21 questions answered

Second homes & investment

Second home or investment is a classification with real consequences for your rate and down payment. How lenders decide, and how rental income counts.

Before the mortgage side, I sold over 1,000 homes here in the Capital District. These answers come from someone who has sat in the agent’s chair at the closing table — not a banker reading you a policy manual.

Do you handle investment properties and renovation loans?

Yes — DSCR loans that qualify on the property's rent instead of your tax returns, and renovation financing that rolls the work into the loan.

The house everyone else scrolled past because the kitchen is orange is frequently the best deal on the street. Start with RENO.

#
How much do I need down on a second home?

Ten percent is the common starting point on conventional second-home financing, and 15–20% gets you the best pricing. That is well below the 15–25% typical on an investment property, which is why the occupancy classification matters so much.

Full breakdown: Second home loans

#
Are second-home rates higher than primary-home rates?

Slightly. Second-home pricing carries a modest adjustment over a primary residence, but it is far closer to primary pricing than to investment-property pricing. Credit score, down payment and reserves move your rate more than the occupancy type does.

Full breakdown: Second home loans

#
Can I rent out my second home?

On most programs, occasional short-term rental is acceptable as long as you keep exclusive control of the property and do not turn it over to a management company. If the plan is to rent it out most of the year, it is an investment property and should be financed as one — often with a DSCR loan.

Full breakdown: Second home loans

#
How far does a second home have to be from my primary residence?

There is no single mileage rule anymore, but underwriters do want the arrangement to make sense — a "vacation home" ten minutes from your house invites questions. A camp on Lake George when you live in Colonie is an easy story to tell.

Full breakdown: Second home loans

#
Can I use a second home as a first step toward retirement?

Yes, and plenty of buyers do — buy it now as a second home, move into it later. Financing it as a second home today is entirely legitimate if that is how you will use it today.

Full breakdown: Second home loans

#
Does a second home qualify for FHA or VA?

Generally no. FHA and VA are owner-occupancy programs. Second homes are financed conventional, or jumbo above the conforming limit, or through a portfolio program.

Full breakdown: Second home loans

#
What if I am buying a seasonal camp with no heat or year-round road access?

That is the real hurdle on Adirondack property. Most conventional programs require the home to be habitable year-round with legal, maintained access. Send me the listing before you make an offer and I will flag it in an afternoon.

Full breakdown: Second home loans

#
What is the difference between a second home and an investment property?

A second home is one you use yourself and do not rent on a regular basis; it requires from about 10% down and prices near primary-residence rates. An investment property is purchased to generate income, typically requires 15% or more down, and carries higher pricing. The decisive difference is that rental income can help you qualify for an investment property but generally cannot for a second home.

Full breakdown: Second home vs. investment

#
How much down payment do I need for a vacation home?

Second home financing generally starts around 10% down for well-qualified borrowers. Investment property purchases typically require 15% for a single unit and more for two-to-four unit properties or lower credit scores. Exact requirements vary with credit, reserves and the number of properties you already finance.

Full breakdown: Second home vs. investment

#
Can I use rental income to qualify for an investment property?

Not automatically. On conventional financing, rental income is generally treated as stable income only once it appears on Schedule E of your tax returns, or where you can document a history of owning and managing rental property. Buyers purchasing their first rental are often told the projected rent cannot be used at all, even with a signed lease in hand. A DSCR loan is the usual answer in that situation, because it qualifies on the property income and requires neither tax returns nor landlord history.

Full breakdown: Second home vs. investment

#
Does Airbnb income count toward qualifying?

Usually not in the way buyers hope. Short-term rental income is treated far more conservatively than a signed long-term lease and frequently cannot be used to qualify at all on conventional financing. A DSCR loan is often the better route when the income projection is central to the purchase.

Full breakdown: Second home vs. investment

#
Are investment property rates higher?

Yes. Investment property financing carries a risk-based price adjustment, so the rate runs above what the same borrower would get on a primary residence or a second home. The gap varies with down payment and credit score, and a larger down payment reduces it meaningfully.

Full breakdown: Second home vs. investment

#
Can I buy an investment property in an LLC?

Often yes, particularly on DSCR and other non-QM investment products, which is one reason investors choose them. Conventional financing generally requires the loan to be in your personal name. If entity vesting matters for liability or partnership reasons, raise it before you apply rather than at closing.

Full breakdown: Second home vs. investment

#
What is a DSCR loan and when does it make sense?

A DSCR loan qualifies the borrower on the property income rather than personal income, so no tax returns or W-2s are required. It makes sense for investors whose returns show significant write-offs, who already carry several financed properties, or who want to vest in an LLC. It only applies to investment property, never to a second home.

Full breakdown: Second home vs. investment

#
When is a DSCR loan the wrong choice?

DSCR is the best tool in the business for scaling a rental portfolio. It is also a rate premium over agency financing, and there are files where using it costs you money for nothing.

You only own one or two rentals and your DTI is fine. If conventional will still approve you, take it. Agency investment-property financing is cheaper than DSCR. DSCR earns its premium when your DTI runs out, not before. Conventional loans →

You’re going to live in the property. DSCR is non-owner-occupied by definition. There is no owner-occupied DSCR, and misrepresenting occupancy on a mortgage application is fraud, not a strategy. FHA 2-4 unit →Conventional loans →

The property doesn’t cover its own payment. If market rent won’t cover principal, interest, taxes, insurance, and HOA at roughly a 1.0 ratio, the loan doesn’t work. Some investors go below 1.0 with more down payment, but a badly negative property is a no. Run the numbers →

You have less than about 20% to put down. DSCR tops out around 75-80% LTV on a purchase and lower on cash-out. This is not a low-down-payment program and it never has been. Talk through options →

It’s a short-term rental with no history in a hostile town. Some investors will use projected short-term rental income, but many Capital Region towns restrict STRs. No permit and no history means no usable income. Talk to Brian →

You want the lowest possible rate above all else. DSCR trades documentation ease for price. If you’re willing to fully document income and your ratios work, agency financing wins on rate every time. Compare programs →

Full breakdown: DSCR loans

#
What does a DSCR loan use instead of my income?

DSCR doesn't look at your income at all — that's the whole point. It looks at the property's. Here's what goes into the ratio and what gets left out.

What the ratio uses: Market rent from the appraisal — A 1007 rent schedule establishes market rent. On a tenant-occupied property, the lower of actual lease rent or market rent typically governs. The existing lease — A signed lease at or above market is the cleanest documentation there is. Short-term rental income — Some investors will use a 12-month AirDNA or platform statement history where local rules permit STRs. Gross rent on multi-unit properties — Each unit’s rent rolls into the total on 2-4 unit and small multifamily deals. Your credit score and reserves — Not income, but they set your pricing tier and LTV ceiling — they matter enormously. Entity ownership — You can close in an LLC, which most agency loans won’t allow. Good for liability and for keeping the loan off your personal credit.

What DSCR ignores entirely: Your personal income — No paystubs, no tax returns, no W-2s. Not requested, not reviewed. Your debt-to-income ratio — Never calculated. This is why DSCR works when you own eight properties and conventional has stopped returning your calls. Your employment — No verbal verification of employment, no job history questions. Your other properties’ performance — Generally evaluated per property, not portfolio-wide — though some investors cap total exposure. Vacancy you’re currently experiencing — The ratio is built on market rent, not on the fact that the unit is empty this month — though a vacant property may affect LTV with some investors.

The math is simple: monthly market rent divided by the monthly payment including taxes, insurance, and HOA. Above 1.0 and the property pays for itself. Send me an address and a rent number and I’ll tell you the ratio the same day.

Full breakdown: DSCR loans

#
Why do DSCR loans get denied?

DSCR denials are almost always about the property or the paperwork behind the entity — not about you. Which means most of them are avoidable.

The rent schedule comes in below expectation. The buyer used the current tenant's rent or a Zillow estimate, and the appraiser's 1007 lands lower. The ratio drops under the threshold and the loan shrinks or dies. What I do: I pull rent comps before you go under contract and stress-test the ratio at a rent below your assumption. If it only works at the optimistic number, you find out from me, not from an appraiser.

Taxes and insurance were underestimated. The ratio uses the full payment. An upstate NY tax bill or a landlord insurance quote that comes in $200 higher than assumed can flip a 1.05 ratio to a 0.95. What I do: I use the actual current tax bill for the parcel and a real insurance quote, not a percentage estimate. The ratio I quote is built on real numbers.

The entity documentation isn’t in order. Closing in an LLC requires the operating agreement, the certificate of formation, an EIN, and sometimes a certificate of good standing. Missing one stalls the file at the closing table. What I do: We collect the full entity package at the start. If the LLC isn't formed yet or is out of good standing, we fix it while underwriting runs instead of after.

The property is in poor condition. DSCR investors want a rent-ready property. Deferred maintenance, an unfinished rehab, or a unit that can't be legally occupied gets the file declined or repriced. What I do: I review photos and the scope honestly before we submit. A property mid-rehab belongs on a different product, and I'll say so rather than wasting your appraisal fee.

Short-term rental income isn’t permitted locally. The file is built on STR revenue and the town bans or permits-caps short-term rentals. The income becomes unusable overnight. What I do: I check the local rules for the specific town before the file is structured on STR income, and I underwrite to long-term rent as the fallback so the deal survives either way.

Seasoning or cash-out limits. A cash-out on a property bought three months ago runs into seasoning requirements, or the LTV on cash-out is lower than the borrower planned around. What I do: I map the seasoning and LTV rules to your timeline before you count on the proceeds. If we're 60 days short, we plan the closing date around it rather than getting declined.

Full breakdown: DSCR loans

#
Who should not use a second home loan?

A lake house on George or a place near Gore is one of the most common conversations I have. The financing is straightforward — until occupancy, rental plans, or the property type get in the way.

You’re going to rent it out most of the year. That’s an investment property, and calling it a second home on the application is occupancy fraud. Investment financing is a slightly higher rate and completely legitimate — take that instead. DSCR loans →Second home vs investment →

You want to use projected rental income to qualify. Second home loans don’t count rental income at all. If you need the rent to make the numbers work, the file belongs on an investment or DSCR structure. DSCR loans →

The property is too close to your primary residence. Underwriters question a “second home” twenty minutes from your main house. Distance and use pattern both matter, and the file has to make sense. Talk to Brian →

It’s a seasonal camp without year-round access or systems. Many Adirondack and lake properties lack year-round road access, a permanent heat source, or a compliant septic. Agency lenders require all three. Portfolio programs →

You have less than 10% down. Second homes require more down than a primary — typically 10% minimum and often more for condos or higher-priced properties. There’s no 3.5%-down second home. Gift funds →

You need FHA, VA, or USDA pricing. All three are primary-residence only. There is no government-backed second home loan, so the comparison is conventional against portfolio. Conventional loans →

Full breakdown: Second home loans

#
What income has to carry a second home?

Your income has to carry both houses — that's the core of a second home file. No rental offset, no projected income, both full payments counted.

Counts toward qualifying: W-2 wages, self-employment, bonus and commission — Standard documentation under conventional or jumbo rules. Rental income from other properties you already own — Leases plus Schedule E on properties other than the one you’re buying. Retirement, pension, Social Security, annuity — Documented and continuing — very common on second home files. Asset depletion — An excellent fit here. Retirees buying a lake house often have modest taxable income and substantial assets. Reserves — Not income, but second home loans typically require two to six months of reserves on both properties. Plan for it.

Doesn't count (or counts against you): Rental income from the second home — Not counted, period. Even if you have a signed seasonal lease, a second home loan won’t use it. Short-term rental projections — If STR income is part of your plan, the honest structure is an investment loan — and many Lake George area towns regulate STRs anyway. Income offset from renting your primary — Unless you have a lease and meet reserve requirements, your primary payment counts in full. Future retirement income — Income beginning after the purchase can’t be used at application. Time-share or fractional interests — Generally not financeable as a second home on conventional terms.

The honest framing: if the property only works financially when you rent it, tell me that at the start and we’ll write the right loan. Here’s the full comparison.

Full breakdown: Second home loans

#
Why do second home loans get denied?

Second home denials cluster around the property and the occupancy story. In this market, the property is usually the problem.

The property isn’t year-round habitable. No permanent heat source, seasonal-only road access, a non-compliant or undersized septic, or water drawn from a lake. Common on older Adirondack camps and a hard decline on agency loans. What I do: I ask the year-round questions before you write — heat, road, well, septic — and I know which portfolio investors will lend on a true seasonal camp when agency won't.

Occupancy doesn’t hold up. The file says second home and the underwriter sees a rental listing, a nearby primary residence, or a rental management agreement in the file. What I do: We pick the correct occupancy at the start. If your plan includes renting, we write it as an investment loan — the rate difference is small and the deal actually closes.

Reserves fall short. The borrower documents the down payment and forgets that second home loans require reserves on both properties. What I do: I size the full cash requirement — down payment, closing costs, and reserves on both homes — before you're under contract, so there's no gap at underwriting.

The appraisal misses on a unique property. Waterfront and mountain properties have thin comparable data. A lake house with 80 feet of frontage is not comparable to one with 200, and a careless appraisal shows it. What I do: I get local comps to the appraiser with the order and I know which appraisers actually understand Lake George, Saratoga Lake, and the Adirondack market.

DTI can’t carry both payments. Two full mortgage payments, two tax bills, two insurance premiums — and in the Adirondacks, sometimes flood insurance nobody budgeted for. What I do: I run the combined payment with real taxes and a real insurance quote, including flood where applicable, before we go further. You'll know the true number, not an estimate.

Condo or HOA project problems. A resort-style condo with high investor concentration, short-term rental operations, or a hotel-like rental desk fails agency condo review. What I do: I get the questionnaire early on any condo purchase. Resort projects frequently need a portfolio investor and I know which ones will take them.

Full breakdown: Second home loans

#

Didn’t see your question?

Fifteen minutes, no credit pull, no application, no pitch. Worst case you learn something and I don’t get your business.

Keep going

More questions, by topic

Or search all 551 questions →

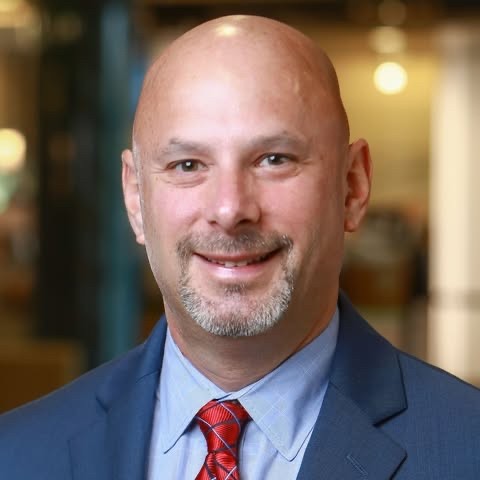
Brian Marchand, Sr. Loan Consultant at New American Funding

Brian Marchand · Sr. Loan Consultant, New American Funding · NMLS #481563

Works on second homes and investment property for buyers and homeowners in Albany, NY and the Capital Region. Licensed in New York State. New American Funding, NMLS #6606 · 18 Computer Dr E, Suite 103, Albany, NY 12205.

About Brian