Home  /  Q&A  /  Income & self-employed
78 questions answered

Income & self-employed

Income is the single most misunderstood part of a mortgage file, and if you are self-employed it is where deals are won or lost. How underwriters actually calculate what you earn — and the add-backs most lenders never look for.

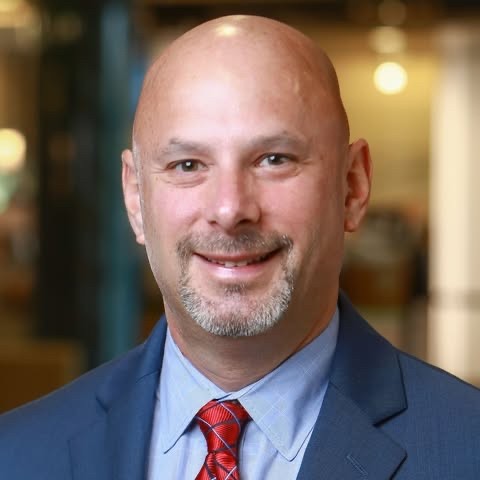
Before the mortgage side, I sold over 1,000 homes here in the Capital District. These answers come from someone who has sat in the agent’s chair at the closing table — not a banker reading you a policy manual.

I'm self-employed — can I still qualify?

Definitely. Beyond traditional loans, there are bank-statement programs that qualify you on your deposits rather than tax returns — built for business owners and 1099 earners.

Find the details under Loan Programs, then let's talk through your specifics.

#
Does the rate cost more than a conventional loan?

Yes — bank-statement programs price 0.75% to 1.5% higher than a conventional 30-year, depending on FICO, LTV, and reserves. That's the trade for qualifying on deposits. For most self-employed buyers the choice isn't "which loan is cheaper" — it's "which loan actually gets me to the closing table," because the conventional lender told them no.

Full breakdown: Bank statement loans

#
Can I mix personal and business statements?

Some programs allow personal statements if you deposit business income there. Others require dedicated business accounts. If you commingle, we'll pick the program that fits — not the other way around.

Full breakdown: Bank statement loans

#
What's the "expense factor"?

The underwriter assumes a portion of your gross deposits went to business expenses. The default is 50%. If your CPA can document that your actual expenses are lower (say, 30% for a service business), we can use that — which increases your qualifying income.

Full breakdown: Bank statement loans

#
Can I use this to buy a rental property?

Yes — bank-statement loans work on primary, second home, and investment. For pure rental-property qualifying without personal income at all, look at DSCR loans — the income source is the rental itself.

Full breakdown: Bank statement loans

#
How long does it take to close?

Same timeline as a conventional loan — typically 30 to 45 days from accepted offer. Bank-statement docs are actually less paperwork than a full-doc self-employed file (no tax returns, no P&Ls, no CPA-drafted forms) so files often move faster.

Full breakdown: Bank statement loans

#
Can I refinance a bank-statement loan into a conventional loan later?

Yes — if your tax returns eventually show enough documented income, you can refinance out of the bank-statement loan into a lower-rate conventional. Many of my clients do exactly this after 2-3 years of stronger documented income.

Full breakdown: Bank statement loans

#
Why do self-employed borrowers get declined for conventional loans?

Conventional underwriting uses net income after business deductions, typically the bottom line of two years of tax returns. Business owners who legitimately write off vehicles, equipment, home office and depreciation often show a fraction of their real cash flow. The result is a debt-to-income ratio that fails even though the borrower comfortably affords the payment.

Full breakdown: Bank statement vs. conventional

#
How does a bank statement loan calculate income?

The lender reviews 12 or 24 months of business or personal bank statements, totals the qualifying deposits, and applies an expense factor to account for business costs. The remaining figure becomes qualifying income. Because deposits are not reduced by tax deductions, the resulting income is usually far closer to actual cash flow.

Full breakdown: Bank statement vs. conventional

#
Are bank statement loan rates much higher?

They price above agency loans because they are non-agency products held by portfolio investors rather than sold to Fannie Mae or Freddie Mac. How much higher depends on credit score, down payment and documentation period. The relevant comparison is usually not against a conventional rate you cannot get, but against waiting two years to restructure your returns.

Full breakdown: Bank statement vs. conventional

#
How much down payment do I need for a bank statement loan?

Commonly 10% to 20%, varying with credit score, documentation period and property type. Stronger credit and 24 months of statements generally unlock the lower end. Conventional financing can go as low as 3% down, which is part of the tradeoff between the two.

Full breakdown: Bank statement vs. conventional

#
Do I need two years of tax returns for a bank statement loan?

No. That is the central point of the program. You will still document business ownership and time in business, typically through a business license, CPA letter or similar, but the income calculation comes from deposits rather than returns.

Full breakdown: Bank statement vs. conventional

#
Can I use personal bank statements instead of business ones?

Many programs allow either, and which one produces a better result depends on how you move money between accounts. Personal statements sometimes work better for borrowers who pay themselves regular draws. It is worth reviewing both before choosing.

Full breakdown: Bank statement vs. conventional

#
What if I have only been self-employed one year?

Most programs want two years, but some investors consider a one-year history when there is prior related W-2 experience in the same field and strong compensating factors. It is a narrower path with tighter requirements, so it is worth asking rather than assuming the answer is no.

Full breakdown: Bank statement vs. conventional

#
Am I actually draining my accounts to pay for this loan?

No. "Asset depletion" is just the math the lender uses to convert your assets into a hypothetical monthly income for qualifying. You don't liquidate anything, you don't set up automatic withdrawals, and the assets stay yours to invest as you always have. It's a documentation method — nothing more.

Full breakdown: Asset depletion

#
Do I need to be retired to use this program?

Not at all. Retirees are the most common fit, but the program works for anyone who has substantial liquid assets and either doesn't have qualifying income on paper or doesn't want to use it. Business owners, trust beneficiaries, and pre-retirees between W-2s all use it.

Full breakdown: Asset depletion

#
Can I combine asset depletion with other income?

Yes. Social Security, pension, part-time W-2, or rental income can all be added on top of the depleted-asset income. That "blended" file often qualifies for a larger loan than either method alone.

Full breakdown: Asset depletion

#
What about my 401(k) or IRA if I'm under 59½?

Retirement accounts under 59½ are generally excluded from the calculation on most programs — the assumption is you can't access them without a penalty. Once you cross 59½ and the account is unrestricted, we count them at the retirement haircut.

Full breakdown: Asset depletion

#
What's the rate on a DSCR loan?

Typically 1.00% to 2.00% higher than a conventional 30-year investment loan, depending on FICO, LTV, DSCR ratio, and whether you take a pre-payment penalty. The pre-pay option can shave 0.375-0.625% off the rate — worth it if you plan to hold 5+ years.

Full breakdown: DSCR loans

#
Can I use projected rent instead of actual?

Yes. If the property is vacant or you're buying a home to convert into a rental, the appraiser fills out a "market rent schedule" (Form 1007) and that number becomes the qualifying rent.

Full breakdown: DSCR loans

#
How's DSCR different from a conventional investment loan?

Conventional counts your job, W-2s, tax returns, personal debts, and caps you at 10 total financed properties. DSCR doesn't ask about any of that — the property qualifies itself. You can own 40 rentals and still buy #41 tomorrow.

Full breakdown: DSCR loans

#
What about short-term rentals — Airbnb / VRBO?

Most DSCR lenders will use 12 months of trailing rental income from the platform, or an AirDNA report projecting market income. Underwrite is the same — rent divided by PITIA.

Full breakdown: DSCR loans

#
How fast can we close?

Standard 30-45 days. With clean docs and a fast appraisal, DSCR files often close in 21-28 — no personal income underwrite to slow it down.

Full breakdown: DSCR loans

#
Can I buy a house with an ITIN?

Yes. An ITIN mortgage uses your Individual Taxpayer Identification Number in place of a Social Security number. You will generally need two years of tax returns filed with that ITIN, documented income, and 15–20% down. Your immigration status is not part of the underwriting decision.

Full breakdown: ITIN loans

#
Do I need a green card or work permit?

No. ITIN lending does not require permanent residency or an employment authorization document. If you do have an SSN or EAD, though, tell me — you may qualify for FHA or conventional financing at meaningfully better terms.

Full breakdown: ITIN loans

#
How much down payment do I need for an ITIN loan?

Fifteen to twenty percent is typical, and select programs go to ten percent for borrowers with strong credit and reserves. Gift funds from family are allowed on most programs with proper documentation.

Full breakdown: ITIN loans

#
What if I have no credit score?

That is common and workable. We build an alternative credit profile from twelve months of payment history on three or four accounts — rent, utilities, cell phone, and insurance are the usual four. A landlord ledger or cancelled checks will do for rent.

Full breakdown: ITIN loans

#
I get paid in cash. Can I still qualify?

Only for the portion you can document. Cash that never touches a bank account cannot be used. If you are planning to buy in the next year or two, start depositing your income now and file your returns accordingly — that single habit is what makes the file work.

Full breakdown: ITIN loans

#
Are ITIN loan rates much higher?

Higher than conventional, yes — these are portfolio loans the lender keeps on its own books rather than selling. But they are real 30-year fixed mortgages with normal amortization, and you can refinance later if your situation changes.

Full breakdown: ITIN loans

#
Can I buy a two-family with an ITIN loan?

On many programs, yes — one to four units, with you occupying one of them. The rental income from the other units can often help you qualify. This is a popular route in Queens and Brooklyn.

Full breakdown: ITIN loans

#
Can a non-US citizen get a mortgage in New York?

Yes. Foreign national mortgage programs are built exactly for this. You do not need a Social Security number, a US credit score, or US income — you need a passport, documentation from your home country, and typically 25–30% down.

Full breakdown: Foreign national loans

#
How much down payment does a foreign national need?

Twenty-five to thirty percent is standard. The larger down payment is what substitutes for the credit history the lender cannot verify. More down improves pricing noticeably on these programs.

Full breakdown: Foreign national loans

#
Do I need a US visa to buy property here?

Most programs do not require one. Buying US real estate does not require any particular immigration status — it is a purchase, not an immigration matter. A visa can widen your program options, but its absence rarely stops the loan.

Full breakdown: Foreign national loans

#
Can I buy through an LLC?

Yes, and for investment purchases it is common. LLC vesting is available on most foreign national and DSCR programs. Speak with a US attorney and a cross-border CPA before you set the structure — the tax consequences matter more than the financing does.

Full breakdown: Foreign national loans

#
Can I buy a co-op in Manhattan as a foreign buyer?

Financing exists, but co-op boards are the real obstacle. Most New York co-op boards will not approve a non-resident purchaser regardless of financial strength. Condos are the practical answer for foreign buyers — more on the difference here.

Full breakdown: Foreign national loans

#
Can I qualify using the rental income instead of my own income?

Yes. A DSCR loan qualifies on the property’s rent rather than your personal income, which sidesteps translated employment documents and foreign tax filings entirely. For a pure investment purchase it is usually the faster route.

Full breakdown: Foreign national loans

#
What if I am moving to the US for work but have not started yet?

There are programs for exactly that gap. A signed employment offer, relocation documentation, and assets can carry a file before any US income history exists. Reach out before you arrive — the timing is easier to manage in advance.

Full breakdown: Foreign national loans

#
How long do I need to be at my current job to qualify?

The standard is a two-year work history — not two years with the same employer. Job changes inside the same line of work are normal and rarely a problem.

#
Can I get a mortgage if I just started a new job?

Usually yes. An offer letter or employment contract plus a first pay stub is often enough, especially in the same field. Starting a brand new career at the same time you buy is the harder version.

#
Can I qualify if I changed careers?

Yes, if the new field is stable and documented. Relevant schooling or training often counts toward the two-year history, which surprises people.

#
Can I qualify with a gap in my employment?

Usually. A gap under six months typically needs a letter of explanation. A longer one generally means six months back at work before we can use the income.

#
Can I qualify if I am still on probation at my new job?

Frequently yes. A probationary period is not an automatic decline — we document the terms and the start date. Some programs are stricter than others, which is where program choice matters.

#
Can I use overtime income?

Yes, typically averaged over two years, with a letter from your employer that it is likely to continue. Twelve months can sometimes work if the history is strong and consistent.

#
Can I use bonus income?

Yes. Bonuses are generally averaged over two years and need to look consistent rather than one lucky year.

#
Can I use commission income?

Yes. Commission usually requires a two-year history, and once it is more than 25% of your income, tax returns come into it and unreimbursed business expenses can reduce the usable figure.

#
How long do I need to have been receiving bonus or commission income?

Two years is the standard. Twelve months is a case-by-case conversation and depends on the program and how steady the pattern looks.

#
Can I use tips as income?

Yes, and it is more workable than it used to be. Tips reported on pay stubs and tax returns get averaged, typically over two years. Unreported cash tips, unfortunately, do not count.

#
Can I use per diem income?

Generally not. Per diem is usually treated as an expense reimbursement rather than income unless it is taxed and documented as earnings.

#
Can I use rental income from a property I already own?

Yes. Leases plus the tax returns showing it, and most programs count about 75% of the gross rent to account for vacancy and maintenance.

#
Can I use Social Security income?

Yes, with the award letter or benefits statement. Because it is largely non-taxable, most programs let it be grossed up, which raises your qualifying income meaningfully.

#
Can I use disability income?

Yes. The documentation has to show it continuing for at least three more years — a benefit with a scheduled end date inside that window generally cannot be used.

#
Can I use pension or retirement income?

Yes, documented with the award letter, 1099s, and bank deposits. Non-taxable portions can usually be grossed up the same way Social Security is.

#
Can I use alimony as income?

Yes, with the decree and typically six months of proof you are actually receiving it, plus at least three years of remaining payments.

#
Can I qualify if I work two jobs?

Yes, and second-job income is usable with about a two-year history of holding both. It is a very common way buyers here make the numbers work.

#
Can I qualify if I just got a big raise?

Yes. We can generally use the new rate with a pay stub reflecting it and a letter confirming it, rather than dragging your old salary through the math.

#
Can I qualify if I work remotely for an out-of-state company?

Routinely. We document that the arrangement is permanent, not a temporary accommodation. Where your employer sits does not decide where you can buy.

#
Can I qualify if I am paid in foreign currency?

It is harder, and it is doable. Consistency of deposits and conversion documentation carry the file, and it often lands in a portfolio or foreign national program rather than a conventional one.

#
I have a side business that loses money. Does that hurt me?

It can. A business loss on your return generally reduces your qualifying income, even when your W-2 job is strong. Worth reviewing the returns before you apply — sometimes the fix is structural and simple.

#
I have only been self-employed for one year. Any options?

Yes, on some programs — a one-year self-employment history can work when the field experience behind it is documented, and bank statement loans can use twelve months of deposits.

#
Do I have to be a W-2 employee to get a mortgage?

No. W-2 is simply the easiest file to document. Self-employed, 1099, commissioned, retired, and asset-based borrowers all have programs built for them.

#
When should I not use a Non-QM or portfolio loan?

Non-QM is where I close the deals other lenders decline. It is not, however, a reason to skip the cheaper loan. If any of these fit, take the agency loan and keep the money.

You qualify on a conventional or government loan. Non-QM carries a rate premium — that’s the trade for flexible documentation. If FHA, conventional, VA, or USDA will approve you, use it. I’ll tell you when that’s the case. Compare all programs →Conventional loans →

You have little down payment. Portfolio programs are equity-driven. Most want 10-20% minimum, and the best pricing starts around 25%. There’s no 3%-down Non-QM loan. FHA loans →SONYMA + DPAL →

Your credit is in the low 500s with no compensating factors. Non-QM is flexible on documentation, not on everything. Most programs want 620 or better, and the pricing tiers punish weak credit hard. Credit game plan →FHA loans →

You have no reserves. Nearly every portfolio program requires post-closing reserves — three to twelve months depending on the product. Maximum loan with an empty savings account is a decline. Asset depletion →

You have no documentation at all. There is no true no-doc mortgage anymore. Every program needs something: bank statements, 1099s, a P&L, a lease, an asset statement. Something. Talk to Brian →

You need the file to close in ten days. Portfolio underwriting is manual and thorough. It’s reliable, but a conventional loan with an automated approval is faster when speed is the deciding factor. Conventional loans →

Full breakdown: Non-QM & portfolio loans

#
What are all the ways Non-QM can document my income?

The entire point of Non-QM is that income can be documented in ways agency loans won't accept. Here's the full menu — picking the right one is most of the work.

Ways we can document income: Bank statements — 12 or 24 months of business or personal deposits with an expense factor applied. 1099 totals — Contractor income taken from 1099s with an expense factor — simpler than statements and often better priced. CPA-prepared P&L — A profit and loss statement carrying the income, sometimes supported by just two months of statements. One year of tax returns — For a business with a strong recent year that a two-year average would unfairly drag down. Assets converted to income — Asset depletion or asset utilization, dividing eligible assets by a term to produce monthly income. Property cash flow only — DSCR, where the rent qualifies the loan and your personal income is never reviewed. Mixed and blended — A W-2 spouse plus a self-employed borrower, or wages plus rental plus assets on one file.

What still won’t work: Cash that never touched a bank — No deposit record, no return, no 1099 — there’s nothing to underwrite. A business under two years — Nearly universal across portfolio programs, with rare exceptions for prior related experience. Transfers dressed up as revenue — Underwriters back out inter-account transfers and owner contributions from any deposit analysis. Unrealized gains — Crypto or stock appreciation. Liquidate and season it and it becomes an asset, which many programs will use. Income you’re about to lose — A contract ending, a business winding down. The underwriter will ask about continuance. Stated income with nothing behind it — The 2008-era product doesn’t exist. Anyone promising it isn’t going to close your loan.

The skill on these files is matching the story to the program. Same borrower, same assets — the difference between the right program and the wrong one is often $200,000 of purchasing power. Tell me the situation and I’ll tell you which door.

Full breakdown: Non-QM & portfolio loans

#
Why do Non-QM loans get denied?

Portfolio files die from mismatch — the wrong program for the story, or an overlay nobody checked. Very little of it is about the borrower's quality.

The wrong program was selected. A self-employed borrower gets put on a bank statement program when a 1099 or P&L program would have produced far more income, then declines on the calculation. What I do: I run the income under multiple documentation methods before choosing. The program is a decision, not a default, and on these files it's the decision that matters most.

The deposit or income calculation came back short. A loan officer quoted gross deposits without backing out transfers, or applied a 50% expense factor where the borrower expected 15%. What I do: I do the full analysis before you write an offer — every transfer out, the real expense factor, month by month. The number I give you holds up in underwriting.

Investor overlays on property or occupancy. Non-warrantable condo, rural acreage, mixed-use, a manufactured home, or a second-home occupancy on an investor-only program. What I do: I check overlays against the specific property before we order an appraisal, and I keep multiple portfolio investors so one overlay doesn't end the deal.

Reserve requirements weren’t disclosed up front. The borrower planned for down payment and closing costs and gets asked for six months of reserves two weeks before closing. What I do: The full cash requirement — down payment, costs, and reserves — is part of the first conversation, not a late surprise.

Credit events too recent for the program. A bankruptcy, foreclosure, or short sale inside the program's seasoning window. Portfolio seasoning is shorter than agency but it isn't zero. What I do: I know each investor's seasoning requirements. Some will lend one day out of a completed bankruptcy at the right LTV — that's a matching problem, and matching is what I do.

The file was shopped and shopped. The borrower has four credit pulls and three declines from lenders guessing at portfolio guidelines they don't actually know. What I do: One well-matched submission to the right investor beats several hopeful ones. If I don't think a file will close, I'll say so instead of running your credit to find out.

Full breakdown: Non-QM & portfolio loans

#
When is a bank statement loan the wrong tool?

Bank statement loans exist because tax returns are a terrible measure of what a business owner actually earns. But they carry a rate premium, and there are scenarios where paying it is simply a waste of money.

Your tax returns already show the income. If your returns support the loan, take the conventional loan. Bank statement pricing is meaningfully higher, and there is no prize for using an exotic program when the plain one works. Conventional loans →See both side by side →

You’re a W-2 employee. This is a self-employment program. If you’re on payroll, your paystubs and W-2s are cleaner and cheaper documentation than 12 or 24 months of statements. Conventional loans →FHA loans →

Your business is under two years old. Nearly every bank statement investor wants a two-year business history, verified through a license, a CPA letter, or a business listing. A six-month-old LLC with great deposits usually isn’t enough yet. Talk through timing →

Your deposits are mostly transfers between your own accounts. Underwriters back out transfers, owner contributions, loans, and non-business deposits. If your gross deposits look large only because money moves between accounts, the qualifying number collapses. Asset depletion →1099 and P&L programs →

You’re buying an investment property. If the property cash flows, DSCR is almost always cheaper and easier — it doesn’t look at your income at all, so there are no statements to analyze and no expense factor to argue about. DSCR loans →

You need the absolute lowest rate and can wait. If you’re able to file a return that reflects your real income and wait for the next tax year, conventional may open up. That’s a real strategy worth a conversation with your CPA. Talk to Brian →

Full breakdown: Bank statement loans

#
Which deposits count on a bank statement loan?

The whole program comes down to one calculation: what portion of your deposits an underwriter will call income. Knowing how that math works is the difference between a $400K approval and a $700K one.

Deposits that count: Business revenue deposits — 12 or 24 months of business account statements. The qualifying figure is deposits multiplied by an expense factor — typically 50%, or your CPA-stated expense ratio if it’s lower. Personal account deposits — Some investors allow a personal-account program where 100% of qualifying deposits count, which often works better for service businesses that deposit into personal accounts. Consistent recurring client payments — Regular deposits from identifiable customers are the strongest form of this documentation. 1099 income — A 1099-only program uses your 1099 totals with an expense factor instead of statements — often simpler and better pricing for contractors. P&L with CPA preparation — A P&L-only program lets a CPA-prepared profit and loss statement carry the income, sometimes with just two months of statements as support. Co-borrower W-2 income — A spouse on payroll can be blended into the file alongside the self-employment side.

Deposits that get backed out: Transfers between your own accounts — Backed out entirely. This is the single biggest reason a projected approval shrinks. Loan proceeds and owner contributions — Money you put into the business, an SBA draw, a line of credit advance — none of it is revenue. One-time or unusual deposits — A sale of equipment, a legal settlement, a refund. Excluded from the average. Deposits into an account you don’t own — Statements have to be in your name or your business’s name, with your ownership documented. Negative months — A month with net-negative activity usually still counts as a month in the divisor, which drags the average down. Cash you never deposited — If it didn’t hit the bank, it doesn’t exist. This program rewards depositing everything.

Before we order anything, send me 12 months of statements and I’ll run the actual calculation — you’ll know your real number in a day instead of guessing.

Full breakdown: Bank statement loans

#
Why do bank statement loans get denied?

These files rarely die on credit. They die on the deposit analysis, the business verification, or the property — and every one of those is knowable up front.

The deposit analysis comes back lower than expected. A loan officer eyeballed gross deposits and quoted a number. Underwriting backed out transfers and owner contributions and the qualifying income dropped 40%. What I do: I run the full deposit analysis myself before you write an offer — transfers out, expense factor applied, month by month. The number I give you is the number underwriting will find.

The two-year business existence can’t be verified. No business license in the state database, no CPA willing to write a letter, no web presence, an LLC formed more recently than the business actually started. What I do: We assemble the verification package at pre-approval: license, CPA letter, client contracts, the Secretary of State filing. If the entity is newer than the business, we document the predecessor.

The CPA won’t confirm the expense ratio. The borrower claims a 15% expense ratio to boost income, then the CPA declines to sign a letter supporting it and the file reverts to the default 50%. What I do: I ask the expense-ratio question at the start and confirm the CPA will actually stand behind it in writing. If they won't, we build the file at the default and set your expectations honestly.

Statements have gaps or missing pages. A month missing, a summary page instead of a full statement, a downloaded PDF that isn't the official bank document. Underwriting rejects it and the clock keeps running. What I do: I tell you exactly what to pull — all pages, official statements, every month, every account — in the first conversation, and I check completeness before submission.

The property or occupancy doesn’t match the program. Bank statement investors have their own overlays: some won’t do non-warrantable condos, rural acreage, or second homes. The income works and the property kills it. What I do: I match the property type to the right investor before submission rather than discovering an overlay in underwriting. I keep several bank statement investors, not one.

Credit or reserve overlays nobody mentioned. These programs price by credit tier and require reserves — often three to six months. A 660 score with no reserves gets a very different answer than the rate sheet implied. What I do: I quote you against your actual credit tier and reserve position from the start. No rate sheet fantasy, and no surprise cash requirement two weeks before closing.

Full breakdown: Bank statement loans

#
Who should not use an asset depletion loan?

Asset depletion is how a retiree with two million in the market buys a house without a paystub. It's an elegant solution to a real problem — and it's the wrong answer in these situations.

You have documentable income. If your returns, paystubs, or 1099s support the loan, use them. Asset depletion is a workaround, and workarounds price higher than the standard path. Conventional loans →Jumbo loans →

Your assets are mostly in retirement accounts you can’t access. Most programs require you to be at or near retirement age to count retirement funds, and many discount them significantly. A 45-year-old with a large 401(k) and no taxable brokerage often doesn’t clear the math. Talk it through →

Your assets are illiquid. Real estate equity, a private business interest, a collection, crypto held in a wallet. If it can’t be verified on a statement and liquidated, it generally won’t depleted. Portfolio programs →

The assets aren’t seasoned or aren’t yours. Money that arrived last week, funds in a relative’s name, or an account you’re merely a signer on. Underwriting needs two to three months of history and clear ownership. Gift funds →

You’d be spending your entire cushion to close. The program divides your assets into a monthly income figure — but you still need the down payment, closing costs, and reserves on top. If closing empties the account, the math stops working. Talk to Brian →

You’re buying an investment property. If it cash flows, DSCR is simpler and cheaper. Asset depletion is built for primary residences and second homes. DSCR loans →

Full breakdown: Asset depletion loans

#
Which assets can actually be depleted into income?

There's no mystery to the calculation — eligible assets get divided by a term to produce a monthly income figure. Which assets are eligible, and at what percentage, is where the real money is.

Assets that can be depleted: Checking and savings — Counted at or near 100% with two to three months of statements. Brokerage and non-retirement investment accounts — Typically counted at 70-80% to account for market volatility and liquidation cost. Retirement accounts — Counted at a reduced percentage, and usually only if you’re 59½ or older — penalty-free access is the test most investors apply. Trust assets you control — Usable when the trust documents establish your access and the statements verify the balance. Proceeds from a business sale — Once the funds are in your account and seasoned, they’re just assets — and often a very large depletion figure. Cash value of certain policies — Some investors allow the accessible cash value of a whole life policy.

Assets that generally can’t: Home equity — Your current house isn’t a depletable asset. Sell it or take a HELOC and the resulting cash becomes one. A private business interest — Value in a company you own isn’t liquid and isn’t usable in the calculation. Unsold crypto — Volatile and unverifiable on a standard statement. Liquidate, deposit, and season it and it counts as cash. Assets in someone else’s name — A parent’s account, a sibling’s brokerage. Not yours, not usable — though a documented gift is a different conversation. The down payment and closing funds — Money you’re spending to close can’t simultaneously be depleted as income. The calculation runs on what remains. Unseasoned deposits — A large transfer that arrived recently needs sourcing and seasoning before it can be counted.

Send me statements and I’ll run the depletion figure against several investor formulas — the divisor and the haircut percentages vary a lot, and the spread between the best and worst formula on the same assets is often six figures of purchasing power.

Full breakdown: Asset depletion loans

#
Why do asset depletion loans get denied?

These files fail on documentation, not on wealth. The borrower is usually far more qualified than the loan they were declined for.

The wrong assets were counted. A loan officer added up every account statement including a 401(k) for a 48-year-old and quoted a purchasing power that underwriting cut in half. What I do: I apply the actual haircuts and age rules up front. The number I give you is built on the same formula the underwriter will use, investor by investor.

Assets weren’t seasoned or sourced. A large transfer in from a business account, a recent liquidation, or a wire from overseas. The balance is real but the paper trail isn't there yet. What I do: We map the movement of every dollar at pre-approval and let anything unseasoned sit until it qualifies. Business-to-personal transfers get the letter they need before the money moves.

Market decline between application and closing. The portfolio was valued at application and the market dropped. On a tight file, the updated statement no longer supports the income figure. What I do: I build in cushion rather than qualifying you at the absolute maximum, so a normal market swing doesn't put the file underwater two weeks before closing.

Reserves were forgotten. Depletion income and the reserve requirement are two separate tests. The borrower planned for one and got asked for both. What I do: I size the down payment, closing costs, and reserve requirement as one plan from the start, then run depletion on what's left over.

Trust or entity ownership couldn’t be documented. Assets sit in a trust or an LLC and the governing documents don't clearly establish the borrower's unrestricted access. What I do: We review the trust or operating agreement early. If access is restricted, we find the investor whose rules accommodate the structure instead of arguing with one that can't.

The investor didn’t actually offer the program. The borrower was quoted asset depletion by someone whose lender doesn't have a real one, then got moved to a full-doc product they can't qualify for. What I do: I know which investors have genuine asset-depletion programs and how each one calculates. That's the whole job on these files — matching the story to the right formula the first time.

Full breakdown: Asset depletion loans

#
When is an ITIN loan not the right door?

An ITIN loan is how someone without a Social Security number buys a home in New York. It's a real, legitimate mortgage — and there are situations where a different door is the better one.

You have a Social Security number. If you have an SSN, you have access to FHA, conventional, VA, and USDA — all cheaper than ITIN pricing. Work authorization status matters for some of these, but the SSN opens the standard doors first. FHA loans →Conventional loans →

You have less than about 10-15% down. ITIN programs are portfolio loans and they require real down payment — typically 10% at minimum and often 15-20%. There is no 3.5%-down ITIN loan. Gift funds →

Your income is entirely undocumented cash. ITIN lending still requires income documentation — tax returns filed with the ITIN, bank statements, or 1099s. Cash with no returns and no deposits can’t be underwritten by anyone. Bank statement loans →

You haven’t filed returns with your ITIN. Most investors want one to two years of filed returns under the ITIN. If you have the number but haven’t filed, that’s the first step — and it’s worth starting now. Talk to Brian →

You’re buying an investment property. Most ITIN programs are owner-occupied. If the goal is a rental, DSCR is often available to foreign nationals and ITIN holders on better terms. DSCR loans →Foreign national loans →

You live abroad and have no U.S. credit or residence. That’s a foreign national loan, which is a different product with different rules — usually more down payment but no U.S. credit requirement. Foreign national loans →

Full breakdown: ITIN loans

#
What income and credit work on an ITIN loan?

ITIN underwriting is often more thorough than conventional, not less. The good news is that the same documentation that proves your income also builds your case — and I know how to assemble it.

Counts toward qualifying: Tax returns filed with your ITIN — One to two years, depending on the investor. This is the strongest documentation in an ITIN file. W-2 wages — If you work on payroll, paystubs and W-2s work the same way they do on any other loan. Self-employment income — Returns plus a P&L, or a bank statement program that uses deposits with an expense factor. 1099 income — Contractor income documented on 1099s with an expense factor applied. Bank statement deposits — 12 to 24 months of business or personal deposits when returns don’t reflect the full income. Co-borrower income — A spouse or family member on the loan, with or without an SSN, can be blended into the file. Documented rental income — Existing leases with a deposit history to support them.

Doesn't count (or counts against you): Cash with no returns and no deposits — No lender can underwrite income that leaves no trace anywhere. Income from a business under two years old — Same two-year rule as every other self-employment program. Undocumented family contributions — Money someone gives you monthly isn’t income unless it’s structured and documented as support. One-time payments — A settlement or a one-off job. Usable as down payment, not as income. Income you can’t tie to you — Deposits into an account in someone else’s name, or revenue from a business you can’t document owning.

Credit is handled the same way: if you don’t have a traditional score, we build a non-traditional credit history from twelve months of rent, utilities, insurance, and phone payments. That’s a real, accepted method — not a workaround.

Full breakdown: ITIN loans

#
Why do ITIN loans get denied?

ITIN files get declined for procedural reasons far more than for credit reasons. Most of what kills them is a lender who has never done one.

The lender doesn’t actually have an ITIN program. A borrower gets told yes by someone who assumes their investor list covers it, then gets declined weeks later because no investor on their sheet accepts an ITIN. What I do: I know which investors genuinely lend to ITIN borrowers and what each one requires. That verification happens before you spend money on an appraisal, not after.

The ITIN itself has lapsed. ITINs expire if they haven't been used on a return in three consecutive years. An expired number stops the file cold. What I do: I verify the ITIN is current at the first conversation. If renewal is needed, we start that with the IRS immediately and build the timeline around it.

Returns weren’t filed, or were filed without the ITIN. The borrower has income but filed under a different number, or didn't file at all. Most investors need returns tied to the ITIN. What I do: We identify this on day one. If filings are missing, I'll tell you honestly what the timeline looks like and what to do first — usually working with a tax professional before we apply.

Credit couldn’t be established. No traditional score and no alternative tradelines assembled, so the file has nothing to underwrite against. What I do: I build the non-traditional credit file deliberately: twelve months of rent verified by the landlord, utilities, insurance, phone. Assembled properly it satisfies the requirement.

Down payment funds couldn’t be sourced. Cash saved at home, funds wired from abroad, or a family gift with no documentation. The money is real and the paper trail isn't. What I do: We source and season every dollar before it matters. Cash gets deposited and seasoned on a schedule, international transfers get documented at both ends, gifts get proper letters.

Program overlays on property or occupancy. ITIN investors often restrict property types — no non-warrantable condos, no rural acreage, owner-occupied only. A fine borrower gets stopped by the house. What I do: I match the property to the investor's overlays before submission. If the house doesn't fit one investor, I know which one it does fit.

Full breakdown: ITIN loans

#
Who should not use a foreign national loan?

Foreign national lending is a specialty product for buyers with no U.S. credit and no U.S. residency. It works well — and if any of these describe you, there's a cheaper path.

You have a Social Security number or a green card. Permanent residents and most visa holders with an SSN can use conventional, FHA, and even VA financing. Don’t pay foreign national pricing if you have access to agency loans. Conventional loans →FHA loans →

You have an ITIN and file U.S. returns. ITIN programs are generally cheaper and require less down payment than foreign national loans. If you have filed returns under an ITIN, start there. ITIN loans →

You have less than 25-30% to put down. Foreign national programs are down-payment driven — typically 30% and rarely below 25%. Without that equity there isn’t a program to fit. Talk to Brian →

You need to close in under three weeks. International documentation takes time: translated documents, a reference letter from a foreign bank, funds transferred and seasoned in a U.S. account. Rushing it is how these files fail. Talk through timing →

You can’t move funds into a U.S. account before closing. Nearly every investor requires the down payment, closing costs, and reserves to be in a U.S. institution and seasoned. Money that has to arrive the day of closing is a problem. Talk to Brian →

You want an owner-occupied primary residence. Most foreign national programs assume second-home or investment use. Occupancy plans change which investors will look at the file — worth clarifying before we start. Second home loans →DSCR loans →

Full breakdown: Foreign national loans

#
What documentation replaces U.S. income and credit?

Without U.S. tax returns or a U.S. credit report, the file is built on international documentation and assets. Here's what actually gets accepted.

Counts toward qualifying: Foreign employment income — An employment letter and paystubs from your employer abroad, translated into English and converted to U.S. dollars. Foreign tax returns or equivalent — Whatever your country’s filing is, with a certified translation. A letter from a foreign accountant — For self-employed borrowers, a CPA-equivalent letter stating income is frequently accepted in place of returns. Foreign bank statements — Verifying both income deposits and assets. Some investors require a reference letter from the institution as well. Assets in a U.S. account — Seasoned funds covering down payment, closing costs, and reserves — typically six to twelve months of payments in reserve. Rental income on a DSCR structure — If the property cash flows, many foreign national deals are written as DSCR loans — no personal income documentation at all.

Doesn't count (or counts against you): A U.S. credit score you don’t have — Not required on these programs. Instead, investors want two to three international credit reference letters — a bank, a landlord, a utility. Untranslated documents — Everything needs a certified English translation. An untranslated statement is not documentation. Funds still sitting abroad at closing — Money must be in a U.S. account and seasoned. A wire arriving the morning of closing will not satisfy underwriting. Cryptocurrency — Almost universally excluded as an asset until liquidated into a U.S. bank account and seasoned. Income from a country under U.S. sanctions — A hard stop for compliance reasons, independent of your personal file.

The most common structure I use for international buyers on a cash-flowing property is a DSCR loan — the property qualifies itself and there’s no income documentation to translate at all.

Full breakdown: Foreign national loans

#
Why do foreign national loans get denied?

These deals die on logistics and compliance, not on qualification. Sequencing is the entire job.

Documentation arrives too late or untranslated. Statements and employment letters come in the original language, or a certified translation takes two weeks nobody planned for. The lock expires while we wait. What I do: I give you the full document list with translation requirements at the start and build the timeline around international turnaround, not domestic assumptions.

Funds weren’t moved and seasoned in time. The borrower plans to wire from abroad at closing. Underwriting requires seasoned U.S. funds and the file stops. What I do: We move the money first. Down payment, closing costs, and reserves land in a U.S. account early so seasoning is complete before underwriting asks.

Source-of-funds and compliance review. Large international transfers trigger anti-money-laundering review. Vague or missing documentation about where the money came from stalls or kills the file. What I do: We document the origin of the funds thoroughly and proactively — sale of a property, business proceeds, inheritance — so the compliance review has everything it needs on first pass.

Visa or immigration status doesn’t match the program. Investors have specific rules by visa type and by occupancy intent. A file built for the wrong category gets declined late. What I do: I confirm status and occupancy intent before selecting the investor, then match to the program whose guidelines actually fit rather than hoping for an exception.

Credit reference letters weren’t obtained. The file has no U.S. credit and no international references, so there's nothing for the underwriter to evaluate. What I do: We request the reference letters at pre-approval, because foreign institutions can take weeks to produce them. Three letters, requested early, prevent a last-minute scramble.

Property type or occupancy overlay. Non-warrantable condos, rural acreage, or a primary-residence occupancy claim on an investor-only program. What I do: I check the overlays against the specific property before we order the appraisal, and I keep multiple foreign national investors so one overlay isn't the end of the deal.

Full breakdown: Foreign national loans

#
When can’t I use child support or alimony to qualify?

Support income is real income and it can absolutely buy you a house — but it's also the income type lenders get wrong most often. Here's when it won't carry the file.

The order is new and no payments have been received. Most programs want a documented receipt history — commonly six months, sometimes twelve. A brand-new order with no payment history generally can’t be counted yet. Talk to Brian →

Support ends within three years. Qualifying income needs a three-year continuance. If your youngest ages out in eighteen months, that income generally can’t be used — though the arrears and the remaining term deserve a closer look. Talk it through →

Payments are inconsistent or partial. An order for $1,200 with an actual history of $600 sporadically means an underwriter will use the lower figure or none at all. Consistency matters more than the ordered amount. Talk to Brian →

There’s no court order or written agreement. An informal arrangement, however reliable, usually isn’t usable. A voluntary payment with no order behind it has no enforceable continuance. Talk it through →

The divorce isn’t final. A temporary order sometimes works and sometimes doesn’t, depending on the program. A pending settlement with no executed agreement is generally too uncertain. Divorce and your mortgage →

You’re the one paying support. Support you pay is a debt, not income, and it counts in your DTI. That’s a different conversation — usually about program choice and DTI flexibility. FHA loans →

Full breakdown: Child support & alimony income

#
How do lenders count child support and alimony?

The rules are specific and worth knowing precisely, because a careless loan officer either drops this income or counts it wrong — and both cost you a house.

Counts toward qualifying: Child support with documented receipt — The order plus proof of payments — typically six months of bank deposits, canceled checks, or a state disbursement unit record. Alimony and spousal maintenance — Same standard: the order, the receipt history, and a three-year continuance from closing. Non-taxable support grossed up — Child support is not taxable income, which means it gets grossed up — commonly 15-25% depending on the program. A $1,000 order can count as $1,250 of qualifying income. State disbursement unit records — In New York, the SCU payment history is clean, third-party documentation and the strongest form of proof there is. Support for multiple children with staggered end dates — The portion continuing at least three years is usable even if part of the order ends sooner. Arrears being paid on a documented schedule — Sometimes usable when there’s a consistent payment history and an enforceable order behind it.

Doesn't count (or counts against you): Voluntary payments with no order — No enforceable continuance means no qualifying income on most programs. Support ending inside three years — Generally excluded from qualifying income, even with a perfect payment history. Amounts above what’s actually received — The underwriter uses the documented history, not the ordered figure, when they differ. Payments made in cash — Without a deposit record there’s no documentation — always take support through the SCU or by traceable transfer. A lump-sum settlement — Usable as down payment funds, not as monthly qualifying income. Support you’re owed but not collecting — Arrears without a current payment pattern generally can’t be counted.

The gross-up is the part people miss. Non-taxable income counting at 115-125% of its face value can move your approval by tens of thousands of dollars — and a loan officer who doesn’t apply it will tell you that you don’t qualify.

Full breakdown: Child support & alimony income

#
Why do files built on support income get denied?

Support-income files decline over documentation, not over the income itself. Every one of these is solvable at pre-approval.

Receipt history couldn’t be documented. Payments came in cash or by informal transfer with no clear trail, so the underwriter can't verify a history. What I do: I tell you exactly what to gather — SCU records, bank deposits, canceled checks — in the first conversation. If the history isn't traceable yet, we build a plan to make it traceable going forward.

The continuance fell short of three years. The file was built on support income that ends in two years. The income gets removed and the approval collapses. What I do: I calculate the continuance date off the order at the start. If part of the support ends early, we qualify on the portion that continues and size the loan accordingly.

Received amounts didn’t match the order. The order says $1,400 and deposits average $900. The underwriter uses the lower number and the pre-approval was built on the higher one. What I do: I average the actual deposits, not the order, when I set your number. That way the approval holds when underwriting does the same math.

Missing or incomplete court documents. The order without the full agreement, or a modified order without the modification. Incomplete documents stall the file. What I do: We collect the complete executed package including any modifications before submission, so underwriting isn't chasing documents while your closing date approaches.

The gross-up wasn’t applied. Not technically a denial — but a borrower told they don't qualify when correctly grossed-up support income would have approved them. It happens constantly. What I do: I apply the gross-up the way each program allows. This alone has turned declines into approvals on files I've picked up from other lenders.

Support stopped mid-process. The paying party falls behind between application and closing. Underwriting re-verifies and the income is no longer supportable. What I do: On files carried substantially by support income, I structure with cushion where I can and re-verify early rather than at the closing table.

Full breakdown: Child support & alimony income

#

Didn’t see your question?

Fifteen minutes, no credit pull, no application, no pitch. Worst case you learn something and I don’t get your business.

Keep going

More questions, by topic

Or search all 551 questions →

Brian Marchand, Sr. Loan Consultant at New American Funding

Brian Marchand · Sr. Loan Consultant, New American Funding · NMLS #481563

Works on self-employed and non-traditional income for buyers and homeowners in Albany, NY and the Capital Region. Licensed in New York State. New American Funding, NMLS #6606 · 18 Computer Dr E, Suite 103, Albany, NY 12205.

About Brian